Market Dynamics Shift: Dow Clears 48,000 as Yields Slip & Oil Crashes — 11-12-2025 Wrap
The Dow climbed above 48,000 as long-end yields slipped and oil tumbled. Tech cooled while value and industrials led. Bond markets confirmed the ongoing liquidity realignment Pattern Nexus has tracked since Q3.
The Dow climbed above 48,000 as long-end yields slipped and oil tumbled. Tech cooled while value and industrials led. Bond markets confirmed the ongoing liquidity realignment Pattern Nexus has tracked since Q3.
Jump to a section
Market Dynamics Shift: Dow Clears 48,000 as Yields Slip & Oil Crashes — 11-12-2025 Wrap
The Dow Jones Industrial Average surged into record territory while the S&P stood flat and the Nasdaq lagged — all underpinned by falling long-end yields, a weak oil complex and the looming end of the U.S. government shutdown. This isn’t just a “bounce” — it’s the next structural leg in the Pattern Nexus liquidity-realignment thesis.
Tape & Internals — Risk-On Rotation to Value/Carry
The U.S. equity market displayed a distinct two-tier behavior today: the Dow hit a fresh record while growth/tech lagged. According to the Associated Press, the Dow Jones Industrial Average climbed ~0.7% to a record ~48,254.82, the S&P 500 rose ~0.06% to ~6,850.92, and the Nasdaq Composite fell ~0.3% to ~23,406.46. :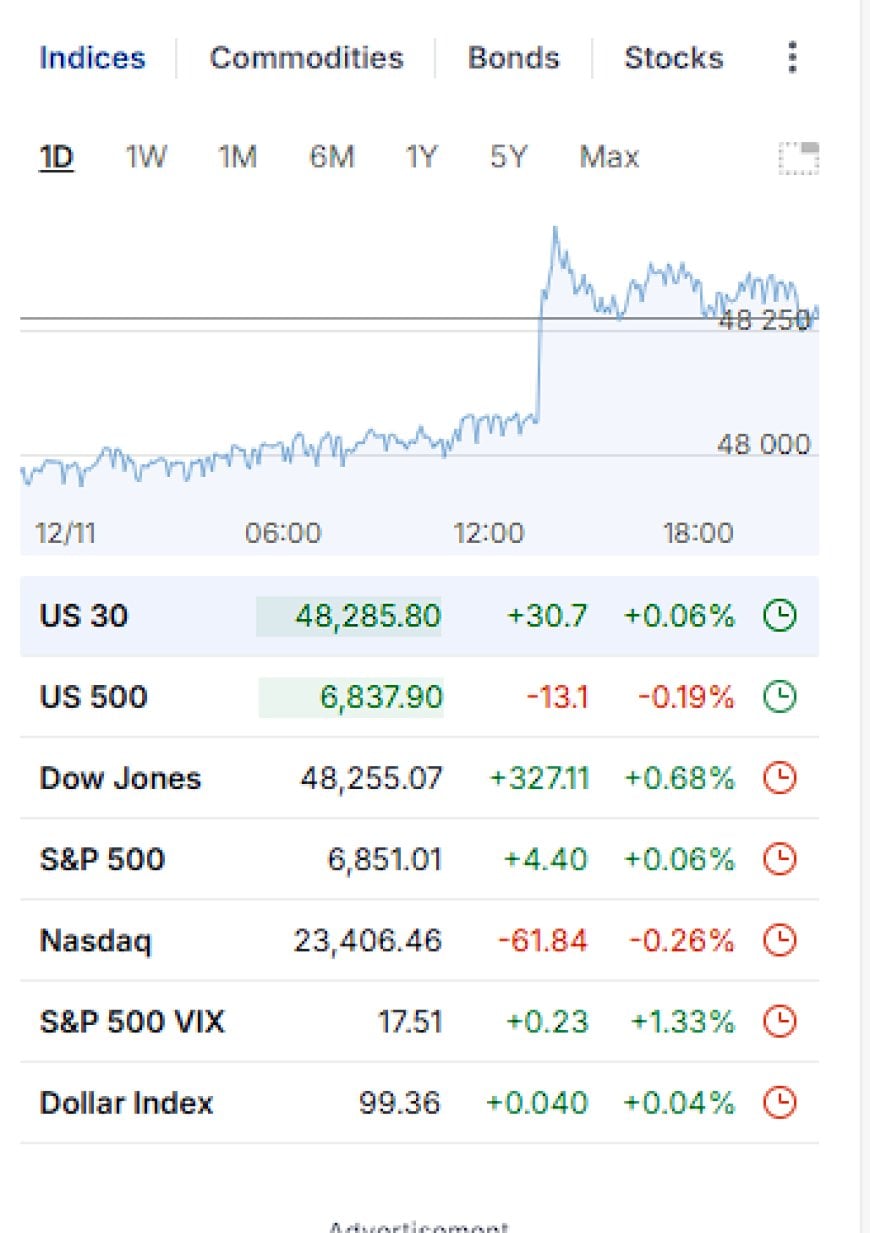
Key observations:
- Value sectors (banks, industrials, airlines) out-performed as the shutdown end-game gained clarity.
- Large-cap tech & “AI-beta” names underperformed — the Nasdaq's weakness echoes the thematic exhaustion we flagged last week.
- Global equity breadth improved: European banks and financials hit record highs amid global relief that “data blackout” may be ending in the U.S.
The tape suggests **rotation within risk** — not outright de-risking. When the Dow rises while tech slips, the window for “carry + liquidity” opens. That aligns with our Pattern Nexus thesis of capital moving from hollow “hype” tech bets into cash-flow and carry plays.
Rates & Curve — Long-End Anchors, Front End Reacts
The bond market reopened after the U.S. Veterans Day holiday with yields slipping across the curve, signalling increased hopes for easier policy ahead. The 10-year Treasury yield closed around 4.067% (+0.05%), the 30-year at 4.661% (-0.02%), and the 5-year 3.666% (-0.05%). The 10-2 spread held at ~31.32 bps.
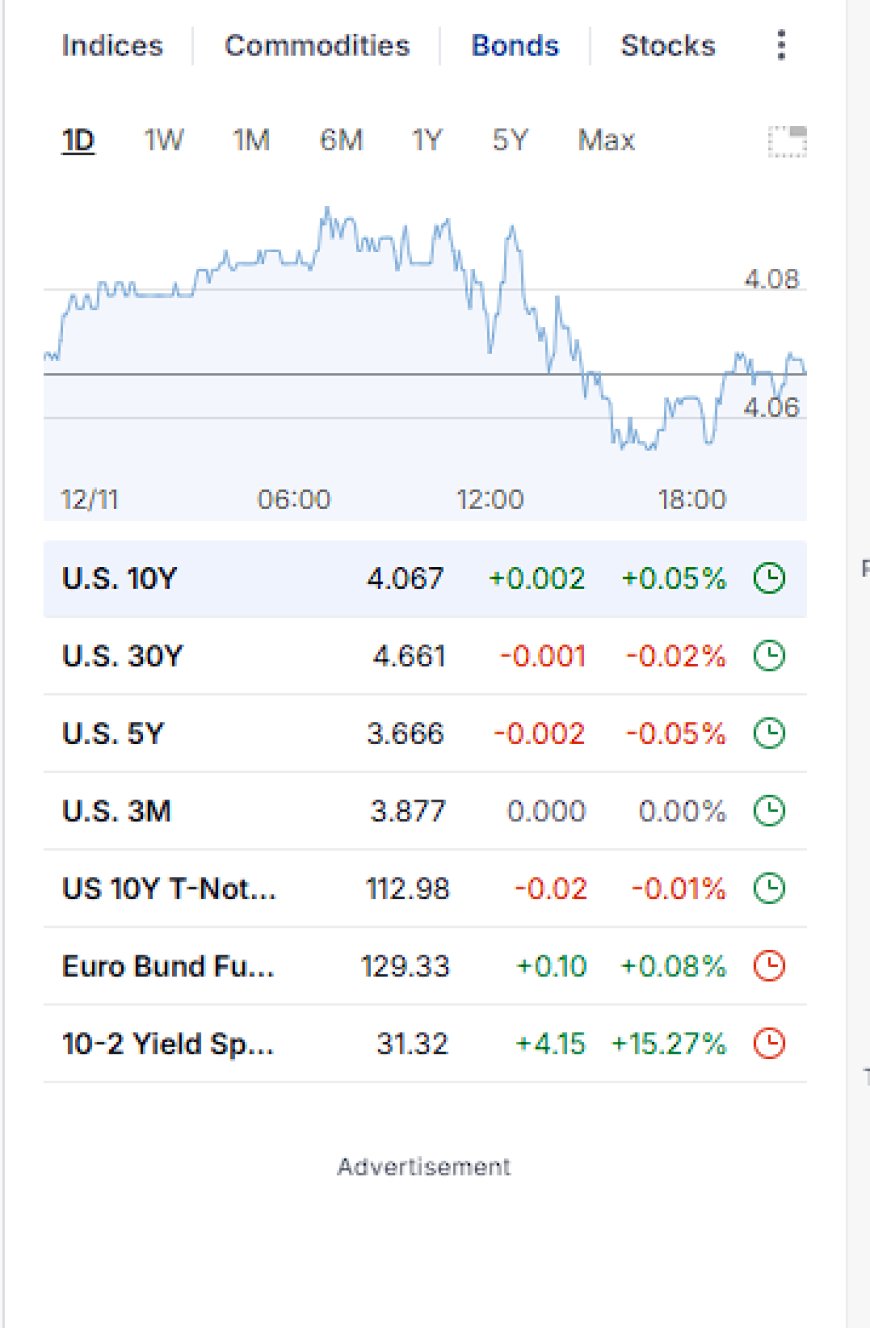
Several structural implications:
- The long-end (30y) declining while the 10-year stabilises suggests *anchor accumulation* — liquidity is being threaded in slowly without blow-off panic.
- The 10-2 spread remaining positive implies the market still supports a mild steepening — a common precursor to easing phases.
- With yields lower, the door opens wider for carry trades, dividend plays, and slower-growth / higher-income equities — exactly what we flagged as the next pivot leg in “Everything Bubble 3”.
message → the plumbing is working again. We saw it last week; today confirms the system’s base layer is expanding subtly and structurally.
Commodities & FX — Oil Slumps, Dollar Flat, Metals Quiet
The commodity complex and FX markets delivered interesting signals:
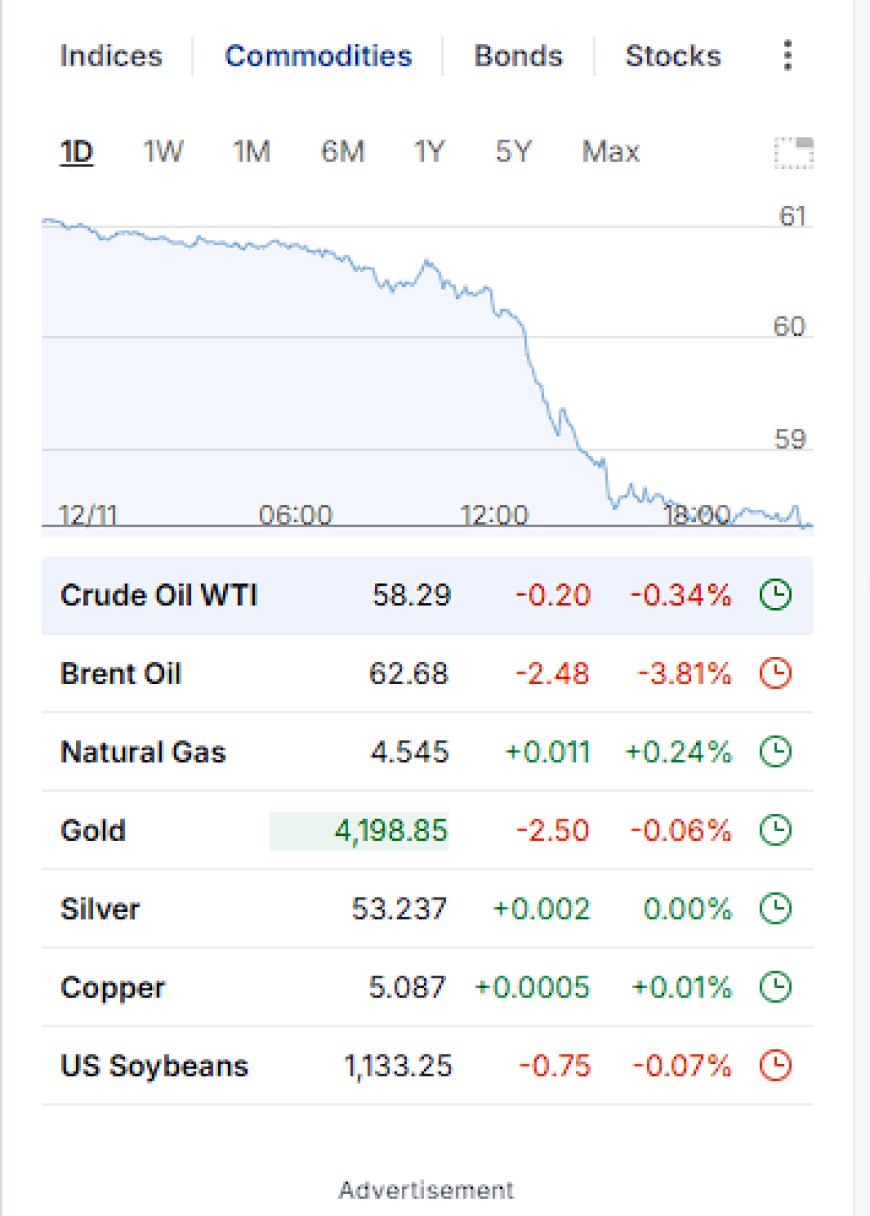
- Oil (WTI) dropped ~3.8% and Brent ~4% — stronger supply signals outweighed demand relief on the shutdown end.
- Gold and silver were mostly flat / modestly higher — indicating risk-on flows didn’t crush metals but weren’t driven by panic either.
- The Dollar Index closed near 99.36 (+0.04%) — essentially stable, which supports the risk-on without dollar stress scenario. (Insert your screenshot.)
The oil slide matters: in a world where liquidity is returning, energy’s weakness suggests demand resilience isn’t being assumed — hence the rotation into carry and value rather than reflation momentum. Watch metals for the next leg if the dollar begins to fade.
Pattern Nexus Narrative — The Transition Persists
If you’ve been tracking the Pattern Nexus framework, today is a confirmation day rather than a surprise. Key points:
- Liquidity plumbing is functioning: Bond yields compress, major indices hit records without full‐blown mania, front end remains sensitive — the ideal condition for structural re-entry.
- Rotation underway: Risk is back, but the leadership has shifted. When the Dow and value sectors outperform tech, you’re seeing capital redeployed, not panic exited.
- Real assets & carry gearing: With yields down and dollar stable, higher-income equities and long-dated duration become attractive even inside a “tightening aftermath”.
The final tipping point comes when the market starts **predicting** rate cuts rather than reacting to them. The shutdown overhang, bond yield drop and rotation we saw today all increase the odds of that being the near-term outcome.
✅ Digest today’s signals carefully: - A record-setting Dow with flat S&P & lagging Nasdaq = structural shift, not bubble blow-off. - Bond yields sliding quietly = plumbing being lubricated. - Oil weak + metals flat = cautious optimism, not runaway inflation. Put together, this is exactly the setup we flagged for H2-2025: **“steady expansion into a larger monetary container.”**
Sources & Further Reading
- Reuters – Global markets rise slightly, U.S. yields fall as shutdown looms
- Associated Press – How major U.S. stock indexes fared Wednesday
- Wall Street Journal – Stocks & indexes Nov 12 2025 live coverage
- The Guardian – Live updates: SoftBank, AI valuations, record bond demand
- Federal Reserve Bank of New York – Money Market Conditions & Balance Sheet (Nov 12 2025)
- Investment Week – Market Movers Blog: SoftBank sells $5.8bn Nvidia stake
📌 Note: Screenshot data pulled from Investing.com dashboards photographed at close of trading Nov 12 2025.
Menene Martaninka?
 Kamar
0
 Karya
0
 Kauna
0
 Ban dari
0
 Wao
0
 Bacin rai
0
 Fushin
0
Nexus (Christopher)
Founder of Pattern Nexus. I research markets, macro, geopolitics, AI, history, ancient systems, and the patterns most people overlook. I’m also building Market Radar, a trading scanner designed to read pressure, risk, confirmation, and setup quality before ch…
Related research
Iran: Escalation Ladder — Reactivation Enabled
The Iran escalation ladder is active again. I examine the October strike risk, the infrastructure-war danger, rising tanker attacks alongsi…
2 shared topics, 2 shared assets.
Housing in 2026: Prices Are High, but the Market Is Barely Moving
The July Case-Shiller index reached another nominal high, but inflation, financing costs and weak sales tell a different story for the marg…
1 shared topic, 3 shared assets.
The Monetary Break — Audio-Video Edition
Episode 4 of the weekly Pattern Nexus audio-video series turns Part 4 of Cycles of Power into a shorter story about how silver redemption, …
2 shared topics, 2 shared assets.
Treasury Turns Long-Bond Buybacks Into a Yield-Control Test
Treasury said it will raise maximum liquidity-support buybacks in the 10-to-20-year and 20-to-30-year nominal coupon sectors from $2 billio…
4 shared topics, 1 shared asset, same research avenue.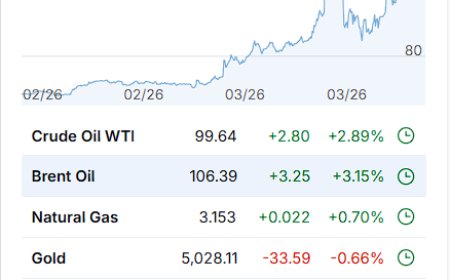
Week Ahead (Mar 16–20, 2026): Central Bank Cluster, War-Risk Premium, and a Market Trading Constraints
Week Ahead (Mar 16–20, 2026): This is a constraint week. Oil risk premium is back, DXY is parked near 100, yields are still restrictive, an…
4 shared topics, 2 shared assets.
CPI (November 2025): Headline Cooling, Energy Re-Acceleration, and the “Two-Month CPI” Problem
5 shared topics, same research avenue.
Record Holidays, Fragile Foundation: Black Friday 2025 vs the ADP Labor Shock
Black Friday and Cyber Week 2025 set new spending records, but the November ADP report showing a surprise 32,000-job loss reveals a fragile…
6 shared topics, same research avenue.
Why Pattern Nexus Exists: The Missing Lens for Macro, AI, and Markets
Pattern Nexus isn’t just another macro or real-estate blog. It’s a systems-level lens that links AI, power, liquidity, housing, and geopoli…
4 shared topics, 1 shared asset.
Sharhu (0)
Security Check
Please complete the captcha to verify you are human.