The Treasury Just Drew Its Line in the Sand — And It’s at the 10-Year
The U.S. Treasury just made its clearest signal yet: the 10-year yield is the line in the sand. This isn’t just another bond market fluctuation — it's a structural defense of financial stability and government financing capacity. When yields approach critical levels, policy firepower follows. The era of passive…
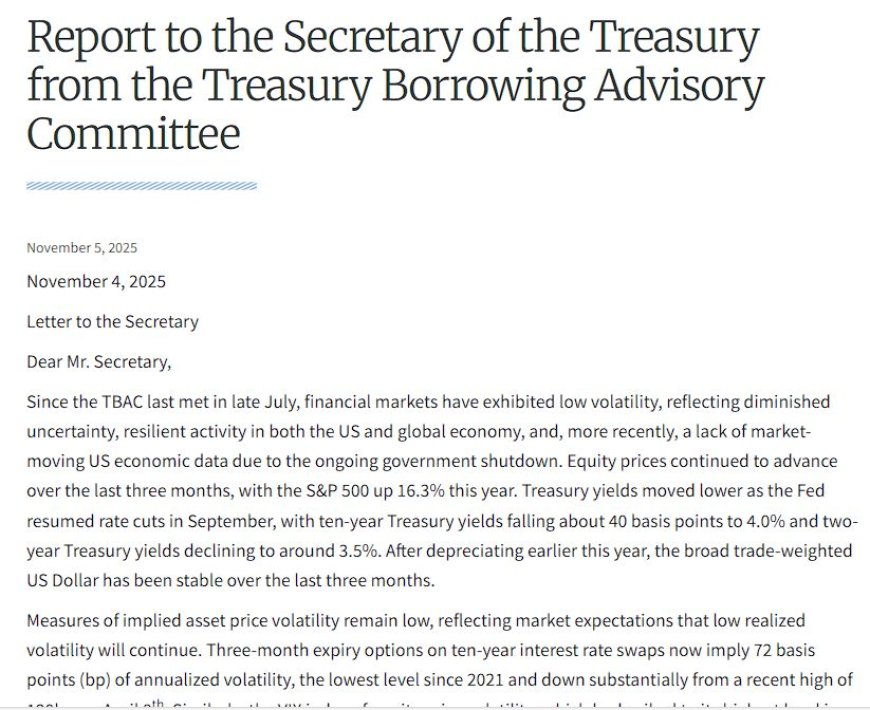
The U.S. Treasury just made its clearest signal yet: the 10-year yield is the line in the sand. This isn’t just another bond market fluctuation — it's a structural defense of financial stability and government financing capacity. When yields approach critical levels, policy firepower follows. The era of passive…
Jump to a section
Treasury Signals Future Auction Size Increases — Markets Eye the 10-Year
November 5, 2025 — Pattern Nexus Macro Brief
The 11-5-2025 Treasury Announcement
Today’s Treasury Quarterly Refunding statement did two things at once:
- ✅ Held nominal coupon auction sizes steady
- ✅ Signaled future increases
This is the classic “hold fire now, telegraph fire later” play.
Treasury’s language: current coupon auctions — including the 10-year — remain unchanged for several quarters, but the Department has begun preliminary consideration of future size increases.
Translation: No supply flood today — but don’t get comfortable.
Key Language Markets Care About
The sentence that lit up trading desks:
“Treasury has begun to preliminarily consider future increases to coupon auction sizes.”
This is forward guidance via issuance, not rates. It’s the supply-side version of “we’re thinking about cutting,” i.e., QE-adjacent signaling via the financing channel rather than the policy-rate channel.
For the longer arc of this shift, see End of the Bond Supercycle and our curve explainer When the 10-Year Won’t Behave.
Is the Treasury Targeting the 10-Year?
- 10-year nominal auction: ~$42B (unchanged)
- 10-year TIPS: ~$19B (unchanged)
- 5-year TIPS: +$1B next month
Does that mean the 10-year is “safe”? No. It means:
- 📌 Treasury is protecting the belly of the curve — for now.
- 📌 Longer-tenor issuance becomes more attractive once yields stabilize.
- 📌 TIPS tweaks help anchor inflation expectations and credibility first.
Context on real yields and term premium: Fiscal Dominance & Sticky Term Premium and Gold vs. the 10-Year.
Desk read: Prepare for more long-end supply when the Fed blinks and term premium cools.
Bills vs. Notes: The Liquidity Mechanics
Short end first, long end later. Why this sequencing?
- Bills load funding without adding duration risk to the market.
- Bills are high-quality repo collateral — useful while liquidity re-pipes and RRP balances normalize. See The Reverse Repo Trap and Fed Repo Surge.
- Front-loading duration at 4.5–5% would lock in expensive debt service costs.
The stance is effectively:
“Bridge with bills now; extend duration later when rates are lower.”
See also: QT Is Over — The System Crossed Its Reserve Floor and The Calm Before the Liquidity Storm.
What the Signal Really Means
This isn’t about today’s prints — it’s about conditioning the market for bigger coupons later. Policymakers are balancing:
- Structurally higher deficits & interest costs
- The need to term out debt
- Global buyers demanding term premium
- Domestic system needs for clean collateral
Call it what it is: long-duration issuance foreshadowing. The 10-year is the benchmark battleground. The 30-year is the final boss.
Broader framework: The Dollar Isn’t Collapsing — It’s Evolving and Systemic Realignment & Digital Sovereignty.
Market Implications
- 📌 Curve Steepening Bias: Front end pinned by policy expectations; the long end prices looming supply.
- 📌 10-Year Real Yield Watch: If reals stay elevated, Treasury waits; once they fall, issuance shifts long.
- 📌 Buybacks as a Soft Backstop: Curve-management tools to relieve dysfunction pockets.
- 📌 Fiscal–Monetary Convergence: Debt-management guidance ≈ policy signaling. The bond market is now a primary transmission mechanism.
For daily context, see our latest brief: Markets Drop, Fed/Banks Warning.
Sources
Menene Martaninka?
 Kamar
0
 Karya
0
 Kauna
0
 Ban dari
0
 Wao
0
 Bacin rai
0
 Fushin
0
Nexus (Christopher)
Founder of Pattern Nexus. I research markets, macro, geopolitics, AI, history, ancient systems, and the patterns most people overlook. I’m also building Market Radar, a trading scanner designed to read pressure, risk, confirmation, and setup quality before ch…
Related research
The Bond Market Is Exposing the Fed’s Real Problem — And It’s Not Inflation
The 10-year yield reveals the Fed’s real challenge: a shrinking debt-sustainability corridor the market refuses to accept. Here’s why the s…
6 shared topics, same research avenue.
Market Wrap-Up — November 13, 2025: Red Tape, Strong Dollar, and a Fed That Markets Still Expect to Blink
U.S. markets had their worst day in a month as the Dow fell nearly 800 points, AI stocks sold off, and Fed cut odds briefly slipped to a co…
3 shared topics, 1 shared asset, same research avenue.
Market Dynamics Shift: Dow Clears 48,000 as Yields Slip & Oil Crashes — 11-12-2025 Wrap
The Dow climbed above 48,000 as long-end yields slipped and oil tumbled. Tech cooled while value and industrials led. Bond markets confirme…
4 shared topics, 1 shared asset, same research avenue.
Markets Melt Higher as Liquidity Pressure Softens — Daily Wrap-Up (Nov 10, 2025)
Equities surged, metals ripped, volatility collapsed, and bond yields stabilized — the exact structural setup Pattern Nexus has been mappin…
3 shared topics, 1 shared asset, same research avenue.
The Silent War-Chest: Why the Fed & Treasury Are Hoarding Cash — And Preparing to Control Yields
Overnight repo usage jumps. The TGA surges toward $1T. Washington isn’t “saving.” It’s loading ammunition — to defend the bond market and …
4 shared topics, 1 shared asset, same research avenue.
Sharhu (0)
Security Check
Please complete the captcha to verify you are human.