10-year treasury
Automatically indexed from the existing article tag.
Theses, forecasts, models, and paths
No published research objects yet
This topic is ready for editors to connect a thesis, forecast, model, or research path.
Latest articles
 Article · related
Fed Just Hiked Into a 5% 10-Year: Why the Next Liquidity Cycle May Arrive Faster
The Federal Reserve just raised the federal-funds target to 3.75%–4.00% while the 10-year Treasury closed at 5.01%, the 30-year at 5.35%, and the real 30-year at 3.09%. Pattern Nexus correctly identified the September hike risk and the developing QE/liquidity cycle, but underestimated the Fed’s willingness to raise rates against an already enormous debt and refinancing burden. This report asks the question almost nobody asks after a rate decision: what does the hike eventually break? It connects the September decision to the $40-trillion-plus federal debt structure, more than $1 trillion of annual federal net interest expense, Treasury issuance, long-end buybacks, Federal Reserve reserve-management purchases, hedge-fund leverage, the Treasury basis trade, private credit, housing, commercial real estate, household cashflow and the 2019 repo-market precedent. The conclusion is not that the Fed has deliberately chosen to create a crash. It is that monetary architecture now allows the Fed to tighten the price of credit while separately protecting reserves and market plumbing. The hike therefore does not invalidate the Pattern Nexus QE thesis. If long rates remain near current levels, it accelerates the transmission mechanism that can eventually force the next phase of liquidity support.
Published Sep 17, 2026 Article · related
QE 2026, Phase Two: When the Long End Forces Duration Control
The Fed already ended QT and expanded Treasury holdings through bill-focused reserve-management purchases, but that repaired the reserve layer without suppressing the long end. With the 10-year Treasury at 4.95%, the 30-year at 5.37%, real long yields near the Pattern Nexus red zone, Treasury doubling long-end buybacks, and August CPI limiting conventional easing, this report calculates the probability that QE 2026 moves into a second phase. It maps the likely program, the names it may use, the dates when it could expand, and the exact yield, reserve, auction, repo, leverage, and credit conditions that could force direct duration absorption.
Published Sep 11, 2026 Article · related
Two Economies, One Balance Sheet: The Unstable Barbell of 2026
Reserve support has returned, but real long rates, fiscal supply, and an AI-energy capital wave are splitting the U.S. economy between capital strength and household fragility. This data-rich Pattern Nexus report maps the four feedback loops connecting Federal Reserve plumbing, Treasury duration, fiscal interest, housing lock-in, household credit, labor churn, AI infrastructure, power demand, dollar rails, and gold. It closes with four scenarios, a public-call audit, and a 90-day trigger dashboard.
Published Sep 9, 2026 Article · related
The Deficit Never Ends: How Annual Shortfalls Build a $78.8 Trillion Federal Debt Load
Most people use “deficit” and “debt” as if they mean the same thing. They do not. This report uses two Pattern Nexus infographics and official CBO and Treasury data to map the annual federal deficit and total federal debt from 2020 through 2040, explain why interest creates a self-reinforcing feedback loop, and show why the 10-year and 30-year Treasury yields—not a political debt-clock slogan—are the market constraint that matters.
Published Aug 22, 2026 Article · related
The Price of a Fractured World: Why the 30-Year Treasury Is Sending a Geopolitical Signal
Something about the global system feels uncomfortable, and the last month of data suggests that feeling has a measurable foundation. The U.S. 30-year Treasury has pushed above 5.3%, real long-term yields are above 3%, the Strait of Hormuz remains severely constrained, U.S. missile inventories are being consumed across multiple theaters, Russia and Ukraine are attacking the commercial infrastructure of the Black Sea, China continues pressure around Taiwan and the South China Sea, new regional defense blocs are forming, tariffs are fragmenting trade, and governments and AI companies are simultaneously competing for enormous amounts of capital. This Pattern Nexus investigation asks whether the long end of the Treasury market is becoming one of the cleanest aggregate prices of a more fragmented world—and separates that thesis from the much weaker claim that the Treasury market itself is failing.
Published Aug 18, 2026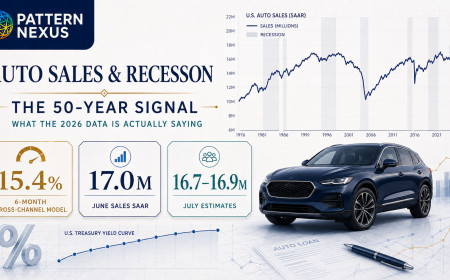 Article · related
Are Auto Sales Predicting a Recession? A 50-Year Regression and the 2026 Signal
Vehicle sales normally weaken before recession becomes obvious elsewhere. Pattern Nexus reconstructs every U.S. recession since 1976, builds auto-only and cross-channel recession models, audits prices, financing, delinquency and buyer concentration, and explains why strong mid-2026 sales reject an immediate recession call without proving broad household strength.
Published Aug 6, 2026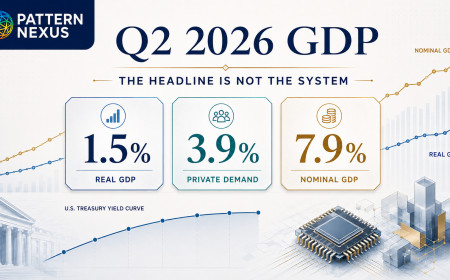 Article · related
GDP Slowed to 1.5%—But the U.S. Economy Did Not Weaken the Way the Headline Implies
Real GDP slowed to a 1.5% annual rate in Q2 2026, but the private domestic economy accelerated to 3.9% while nominal GDP grew 7.9%. This Pattern Nexus analysis separates the headline from the internal economy and explains what consumer spending, business investment, capital-goods imports, inflation, government accounting, Federal Reserve policy, and the 10-year Treasury signal actually mean.
Published Aug 4, 2026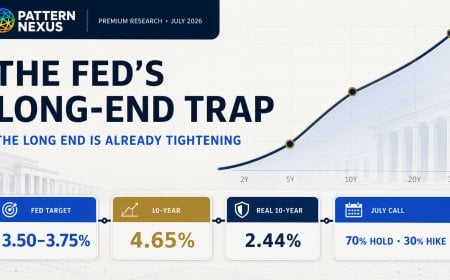 Article · related
The Fed’s Long-End Trap: Why a 4.65% 10-Year Is Already Doing the Tightening
A full July 2026 data reconstruction of the Federal Reserve’s next policy path, showing how a 4.65% nominal 10-year, 2.44% real 10-year, Treasury supply, oil risk and uneven liquidity conditions create a hawkish-hold trap.
Published Jul 27, 2026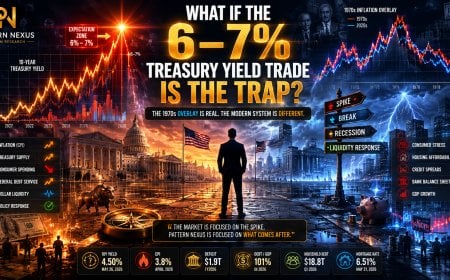 Article · related
What If the 6–7% Treasury Yield Trade Is the Trap?
A lot of smart money is starting to position for a 1970s-style inflation repeat where the 10-year Treasury yield spikes toward 6% or 7%. The chart overlay looks convincing. Inflation today can be lined up against the 1970s if the data is shifted and framed the right way. But Pattern Nexus looks at the system constraint, not just the chart. The question is not whether yields can spike. They can. The question is whether the modern economy, the federal refinancing structure, the consumer balance sheet, and the dollar-based global liquidity system can actually survive a sustained 6–7% long-rate environment. This article argues that the more dangerous trade may be the obvious one: expecting the 1970s to repeat cleanly when the system may instead force a spike, break, recession, emergency response, and renewed liquidity cycle.
Published May 27, 2026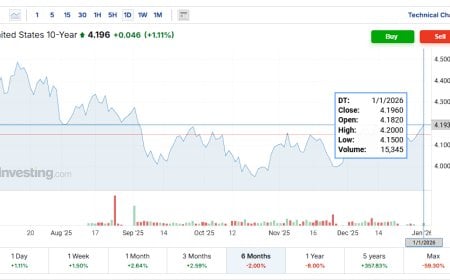 Article · related
The 10-Year Decoupling: Why Long Rates No Longer Follow Cuts
The U.S. 10-year Treasury is no longer responding to policy rate cuts. This article explains the structural decoupling between front-end easing and long-end yields, why this regime persists for months to years, and what conditions eventually force balance sheet expansion.
Published Jan 2, 2026 Article · related
The 10-Year Treasury Pattern and the Return of Repo Operations
The 10-Year Treasury has repeatedly stalled near long-cycle resistance while overnight repo operations have quietly returned after QT. This analysis examines how funding markets, balance-sheet capacity, and rate control interact beneath headline narratives.
Published Dec 29, 2025 Article · related
Daily Market Wrap-Up – December 8, 2025
Daily cross-asset wrap for December 8, 2025. Equities faded into the close while the 10-year Treasury pushed higher toward 4.2% even as markets price in a near-certain Fed rate cut this week. Commodities softened, the dollar treaded water, and crypto stayed bid.
Published Dec 8, 2025 Article · related
Can the 10-Year Treasury Predict Recessions? A 40-Year Pattern Nexus Lens Analysis
A 40-year structural analysis of the US 10-Year Treasury futures market, showing how recessions consistently collide with long-term yield channels, why yield curve inversions continue to matter, and what today’s setup means for the next macro cycle. A full Pattern Nexus Lens breakdown.
Published Nov 20, 2025 Article · related
The Gravity Zone: How the 10-Year Treasury Revealed the Real Neutral Rate
The 10-year Treasury has been oscillating around a hidden 3–4% neutral zone since 2022, revealing the true equilibrium rate the Fed keeps missing. This article breaks down why long rates refuse to fall, why the market no longer trusts traditional rate cuts, how the Treasury’s trillion-dollar TGA fits into the picture, and why quiet yield-curve management is becoming the new operating system of U.S. monetary policy.
Published Nov 18, 2025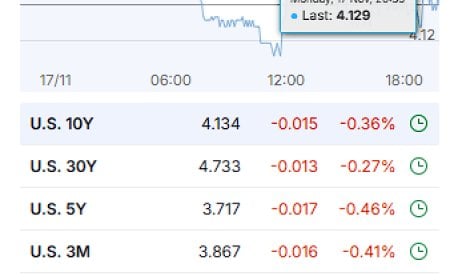 Article · related
Market Wrap – November 17, 2025: Everything Red, but the 10-Year Still Runs the Show
Broad selloff across equities, metals, and crypto, while the dollar firms and the 10-year Treasury continues to defy the Fed’s 2026 rate-cut script.
Published Nov 17, 2025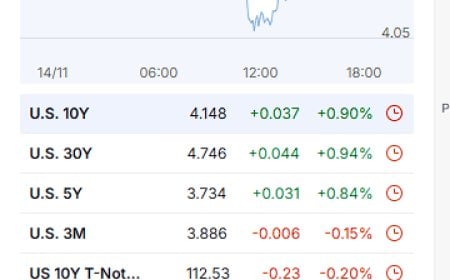 Article · related
The Weekly Market Wrap: The Week the 10-Year Stopped Listening
A volatile week across equities, bonds, commodities, and crypto. Stocks chopped, gold spiked then crashed, Bitcoin cooled off, and the U.S. 10-year Treasury defied the Fed yet again. A deep Pattern Nexus breakdown of what markets are really pricing: liquidity, deficits, AI capex, and the rising cost of capital.
Published Nov 15, 2025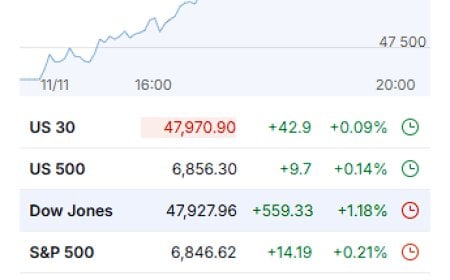 Article · related
Dow Hits Record as Long-End Anchors — Nov 11, 2025 Market Wrap
Dow Jones, S&P 500, Nasdaq, bonds, yield curve, dollar index, volatility, Treasury yields, liquidity cycle, market wrap, Pattern Nexus, November 2025, macro markets
Published Nov 11, 2025