Systemic Risk
Automatically indexed from the existing article tag.
Theses, forecasts, models, and paths
No published research objects yet
This topic is ready for editors to connect a thesis, forecast, model, or research path.
Latest articles
 Article · related
Housing QE by Proxy: How Weaponizing Fannie and Freddie’s Buffers Turns the GSEs into Political Liquidity Machines
Floating the idea of using Fannie Mae and Freddie Mac’s capital buffers to buy mortgages is more than a housing tweak. It’s an attempt to run QE through the GSEs instead of the Fed, turning housing finance into a political liquidity machine and removing the crash pad when the cycle turns.
Published Jan 8, 2026 Article · related
The Household Maintenance Recession: America Is Falling Apart Quietly
Q3 GDP says the economy is strong. The data says households stopped fixing cars, homes, and appliances to survive. This is the household maintenance recession — and it’s invisible in GDP.
Published Dec 23, 2025 Article · related
Gold Didn’t Moon — It Repriced
Gold didn’t fail or stall after QT ended — it repriced early and is now consolidating at a higher structural level. An updated Pattern Nexus breakdown on gold’s role in the current liquidity regime.
Published Dec 21, 2025 Article · related
Why a 150-Year-Old Market Chart Still Haunts Modern Finance
A deep Pattern Nexus breakdown of Samuel Benner’s 19th-century market cycle chart and why it still aligns with modern financial stress windows. This article explains the mechanics behind the “2026 crash chart,” why it appears accurate, what it gets wrong, and how to use it correctly as a risk-regime lens rather than a prediction tool.
Published Dec 21, 2025 Article · related
The Bond Market Is Exposing the Fed’s Real Problem — And It’s Not Inflation
The 10-year yield reveals the Fed’s real challenge: a shrinking debt-sustainability corridor the market refuses to accept. Here’s why the system can’t stay here.
Published Nov 14, 2025 Article · related
$223T Derivatives System: The Hidden Liquidity Fragility Beneath U.S. Banking
The U.S. banking system sits on top of $223 trillion in derivatives — but the real risk isn’t the notional value. It’s liquidity. This deep-dive breaks down how margin calls, collateral chains, FDIC limits, repo plumbing, and Federal Reserve backstops tie together — and why liquidity shocks, not headlines, trigger systemic stress. Includes beginner-friendly breakdowns, research links, historical case studies, and charts.
Published Nov 2, 2025 Article · related
The Liquidity Crunch Nobody’s Talking About: How Repo Stress, Bank Failures, and a “False Surplus” Are Fueling Gold’s Breakout
A hidden liquidity crisis is forming under the surface of global markets. Repo markets are flashing stress, regional banks are reporting fraud-related losses, and gold is breaking all-time highs. This analysis connects the dots — showing how the system is quietly rebalancing through emergency liquidity, fiscal illusion, and a global flight to hard collateral.
Published Oct 17, 2025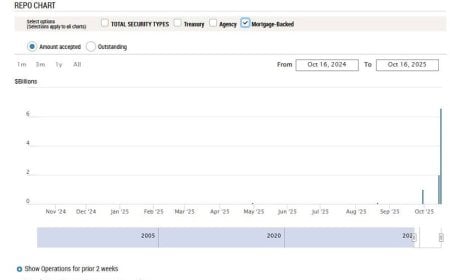 Article · related
🚨 The Fed Just Tapped the MBS Repo Valve — Why That Matters More Than People Think
The Federal Reserve quietly conducted nearly $9 billion in mortgage-backed repo operations after months of inactivity — signaling early liquidity strain in U.S. funding markets. Historically, this is how quantitative easing begins: the Fed provides collateral support before publicly announcing policy shifts. This article examines the data, the 2019 precedent, the QE connection, and what it could mean for 2026.
Published Oct 17, 2025