ADP Weakness, Dollar Break: Labour → Liquidity → Repricing (Nov 11, 2025)
Jump to a section
ADP Weakness, Dollar Break: Labour → Liquidity → Repricing (Nov 11, 2025)
ADP’s new weekly dataset flags late-October job losses as the U.S. Dollar Index cracks a multiyear support. We map the policy path and the collateral plumbing that follows.
What Changed This Morning
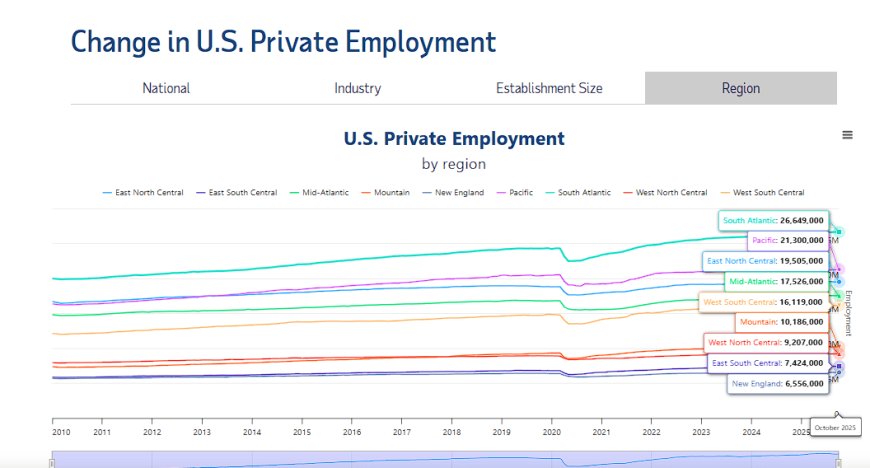
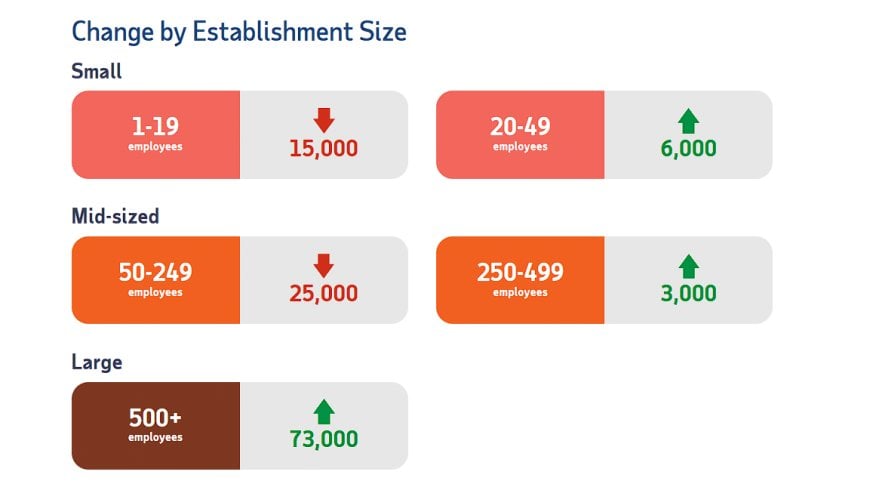
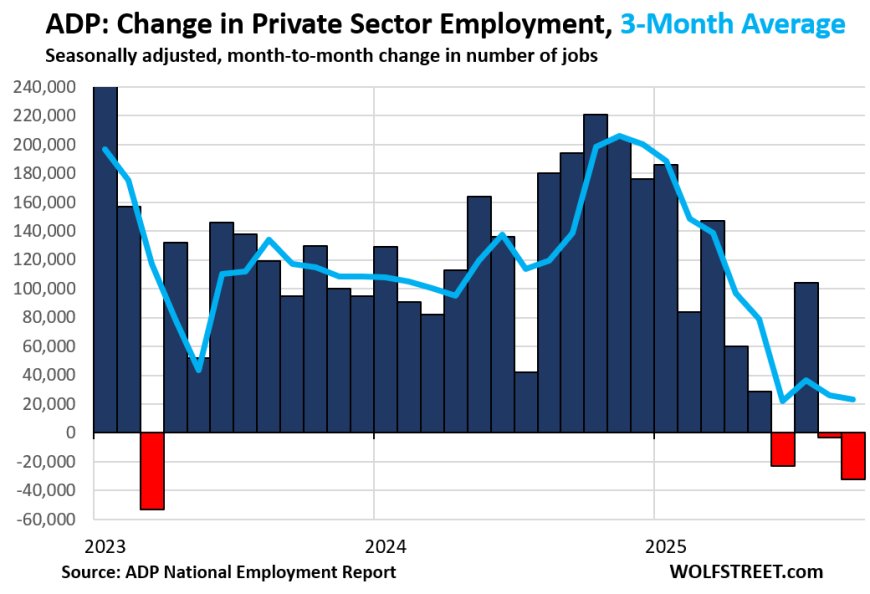
Signal 1 — ADP Weekly: Private employers lost an average of ~11,250 jobs per week in the four weeks ending Oct 25. That’s a late-month deterioration even as the monthly ADP print showed a modest +42k for October.
Signal 2 — NFIB: Small business optimism fell to 98.2, a six-month low, led by weaker earnings and softer hiring plans.
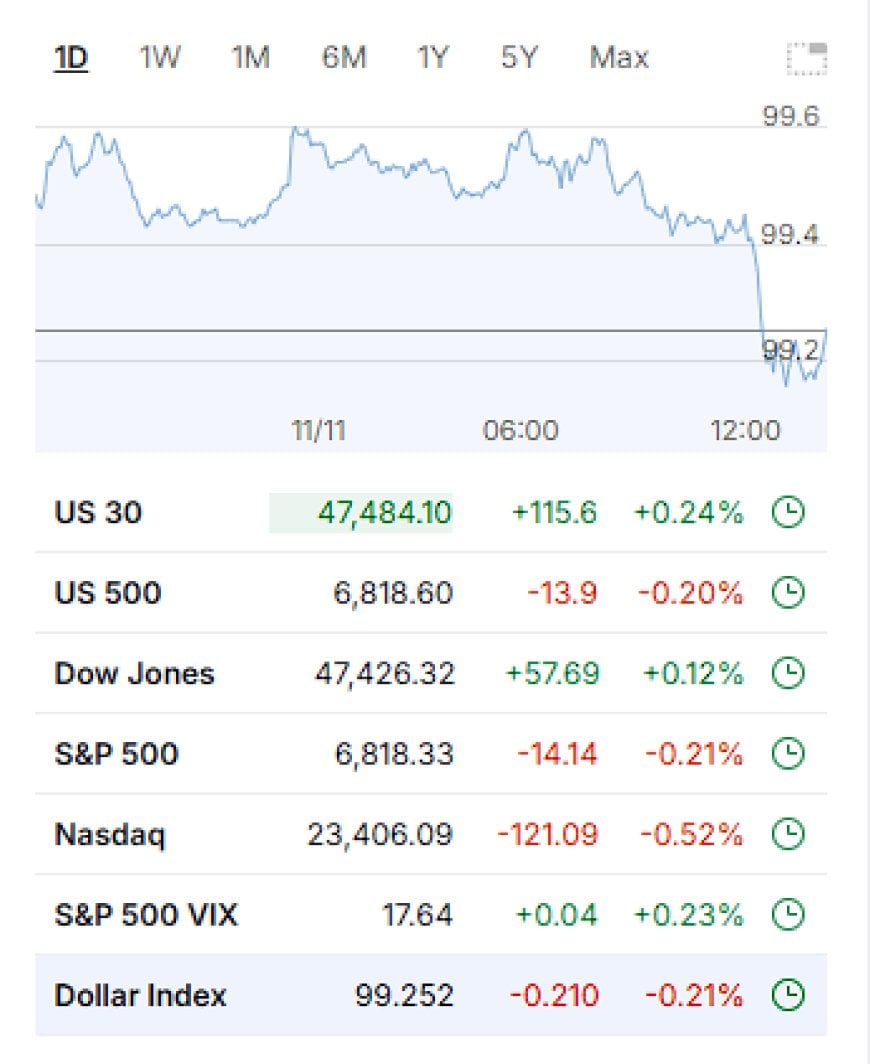
Signal 3 — Dollar: DXY broke below the ~99 shelf, slipping out of the interior channel and into a policy-sensitive zone.
Why it matters: Labour softness → cooler wage impulse → rising rate-cut odds → USD repricing → collateral mix shift across bills/notes/repo. This is the classic feedback loop we track in Tokenized Reserve Era and Everything Bubble 3 (Gold).
Labour: ADP + NFIB
The new high-frequency ADP series provides a four-week moving view with a short lag. The October pattern was uneven: gains clustered early in the month, followed by late-month losses. Layer on the NFIB’s six-month-low in optimism and a downtick in hiring plans, and you have a clean narrative: labour demand is cooling at the margins, especially in white-collar and select services, while wage heat continues to ebb.
Corporate transcripts and layoff trackers have been tilting higher through October alongside AI-driven efficiency pushes. This doesn’t imply a hard stop in employment; it implies a rotational slowdown—the kind that pressures wages first and headline jobs next.
Dollar: Structural Break & Scenarios
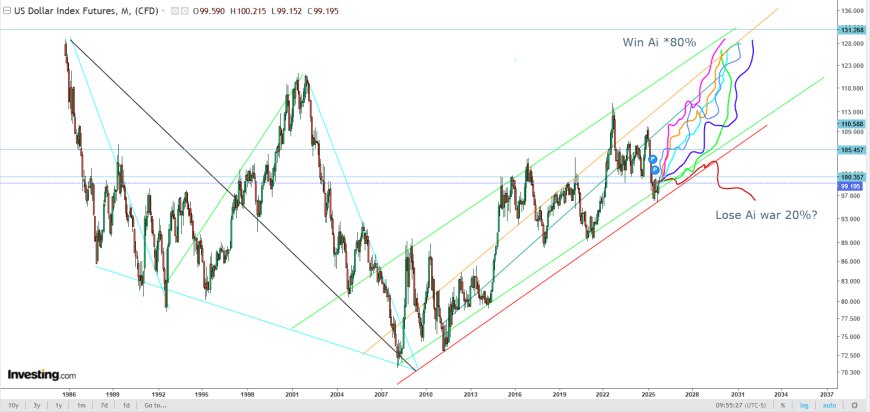
Dollar Index Breaks Support. The U.S. Dollar Index (DXY) cracked below the 99 structural support level this morning — a break that aligns with the soft ADP data and a shift in rate-cut odds.
On the long-term geometry (chart above), the dollar is slipping out of the interior green channel and brushing the underside of the secular support rail. The break occurs at a multi-decade slope intersection, where the 1987–1992 down-cycle, the 2008 recovery slope, and the 2015–2020 carry channel converge. In practical terms, this is where the dollar historically loses trend coherence before entering a policy-dependent repricing regime. The near-term path tilts toward the lower branches of the projection cloud — not a collapse scenario, but the weak-dollar liquidity cycle that reappears whenever the labour market softens faster than policy can adjust.
- Soft-Landing Weak USD: Gradual easing, bills bid, curve bull-steepens, EM/commodities catch a tailwind.
- Growth Scare: Faster cuts, USD down then up on risk-off; gold/outside-money outperform; equities chop.
- Sticky Inflation: Fed delays easing → USD bounces inside channel; rates vol rises; equities wobble.
Liquidity Plumbing & Rates
This is where the mechanics matter. A weaker USD amid labour cool-down typically coincides with: (1) richer bills and front-end collateral preference; (2) repo stability with episodic specials; (3) steady RRP drain if front-end yields drift lower; and (4) relief for global USD borrowers. If the cut-pricing advances, term premia compress and the curve bull-steepens from the front.
Net effect: risk can rally on easier USD liquidity, but cyclical earnings need confirmation. That’s why equities were flat this morning even as the dollar slipped.
Positioning Map
- Exporters & USD-earners abroad
- Real assets with USD sensitivity (gold, selective commodities)
- EM FX beta (case-by-case, dependent on local inflation & external balance)
- Front-end duration / bills in a glide-path easing scenario
- Sticky inflation that delays easing (USD snapbacks)
- Earnings downgrades if labour softness turns to demand softness
- Collateral kinks if issuance mix surprises (bill vs note supply)
Further Reading on Pattern Nexus
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Nexus (Christopher)
Founder of Pattern Nexus. I research markets, macro, geopolitics, AI, history, ancient systems, and the patterns most people overlook. I’m also building Market Radar, a trading scanner designed to read pressure, risk, confirmation, and setup quality before ch…
Related research
Selling U.S. Assets” Won’t Collapse the Dollar — It Collapses Europe’s Dollar Plumbing
Viral claims say Europe could dump U.S. assets to trigger a dollar collapse. In the eurodollar system, that move is closer to setting your …
2 shared topics, 2 shared assets.
When $38 Billion Was a Crisis And $38 Trillion Is a Shrug
A plain-language Pattern Nexus breakdown of how U.S. federal debt went from tens of billions to tens of trillions in a century, why a billi…
4 shared topics, 1 shared asset, same research avenue.
The New Monroe Doctrine: How the 2025 National Security Strategy Confirms the Western Hemisphere Pivot, Digital Dollar Realignment, and the Coming Global Reordering
The 2025 National Security Strategy marks the most dramatic U.S. strategic pivot in decades—re-centering the Western Hemisphere, reviving a…
4 shared topics, 1 shared asset.
Record Holidays, Fragile Foundation: Black Friday 2025 vs the ADP Labor Shock
Black Friday and Cyber Week 2025 set new spending records, but the November ADP report showing a surprise 32,000-job loss reveals a fragile…
6 shared topics, same research avenue.
Fed Cuts Again, Tees Up the End of QT — Exactly as I Called It
The Federal Reserve just delivered its second rate cut of the year and signaled an end to Quantitative Tightening — confirming what I’ve be…
3 shared topics, 1 shared asset, same research avenue.
Markets Drift Higher as Tech Leads and Volatility Rises – Oct 28 2025 Market Roundup
U.S. markets extended gains on Oct 28 2025 as tech stocks outperformed and volatility rose ahead of the Fed meeting. Gold steadied near $4,…
2 shared topics, 2 shared assets, same research avenue.
Why the Dollar Isn’t Weaker: The Shift from Store of Value to System Utility
Even as Fed rates fall below 4%, the dollar remains firm. Here’s why its strength no longer depends on yields — and how tokenization, trade…
2 shared topics, 3 shared assets, same research avenue.
QT Is Over: The System Just Crossed Its Reserve Floor
The liquidity cycle has flipped. QT exhausted the reserve buffer, pushing the system into structural limits the Fed can’t ignore. This isn’…
3 shared topics, 1 shared asset, same research avenue.
Comments (0)
Security Check
Please complete the captcha to verify you are human.