The Oil War Is Becoming a Global Economic War
An extensive Pattern Nexus reconstruction linking the Iran/Hormuz disruption with Ukrainian refinery attacks, diesel shortages, Saudi pipeline damage, U.S. and Venezuelan supply, Cuba’s grid, the dollar system, Treasury financing, Fed tightening, public energy-stock disclosures and the next conditional liquidity cycle. Includes an auditable Pattern Nexus article timeline, four sourced charts and 36 primary/reporting references.
I have been quiet about Iran for a while. Not because there is nothing happening. Quite the opposite.
There are so many moving pieces now that writing about one development without explaining the others would leave out most of what I am actually watching.
Back in January, I started discussing Venezuela, Iran, Cuba, and the possibility that several geopolitical developments were part of a larger restructuring of energy access, trade routes, economic pressure, and global monetary relationships.
I also identified another possible part of that causal chain. I mentioned it without directly publishing the complete scenario because I could not establish the necessary steps. I still cannot establish all of them. This week's meeting between Trump and Xi may clarify an important part of the sequence, or it may change its direction entirely.
But look at what has happened to the machinery underneath the global economy.
Ukraine continues striking Russian refineries and petroleum infrastructure. Iran and the wider Gulf conflict continue constraining crude oil, diesel, LNG, shipping, and insurance. Saudi Arabia's principal pipeline alternative to the Strait of Hormuz has been damaged. Venezuela is entering a new energy-development arrangement involving American capital and U.S. government interests. Cuba remains trapped in a severe fuel and electricity crisis.
The United States is the world's largest crude-oil producer. It also remains a major importer, refiner, exporter, and operator of the financial system through which much of the world's commodity trade is financed.
And now the Federal Reserve has raised interest rates into an energy-driven inflation shock while the long end of the Treasury market sits in the territory I have spent months warning about.
That is only the physical and monetary part of the story.
There is also the ownership part.
Public financial disclosures show that Trump's investment accounts continued buying and selling energy securities during the Iran conflict. Members of Congress have reported energy-stock transactions. Corporate insiders have purchased shares while the market repeatedly reprices the possibility of renewed fighting or a ceasefire.
Some companies and asset owners can receive extraordinary gains while ordinary people absorb higher fuel, food, freight, borrowing, and electricity costs.
That does not establish that every event was centrally planned. It establishes that different events are interacting inside the same economic system, and that the financial consequences are distributed very differently depending on which part of that system someone owns.
That is the story I want to tell you.
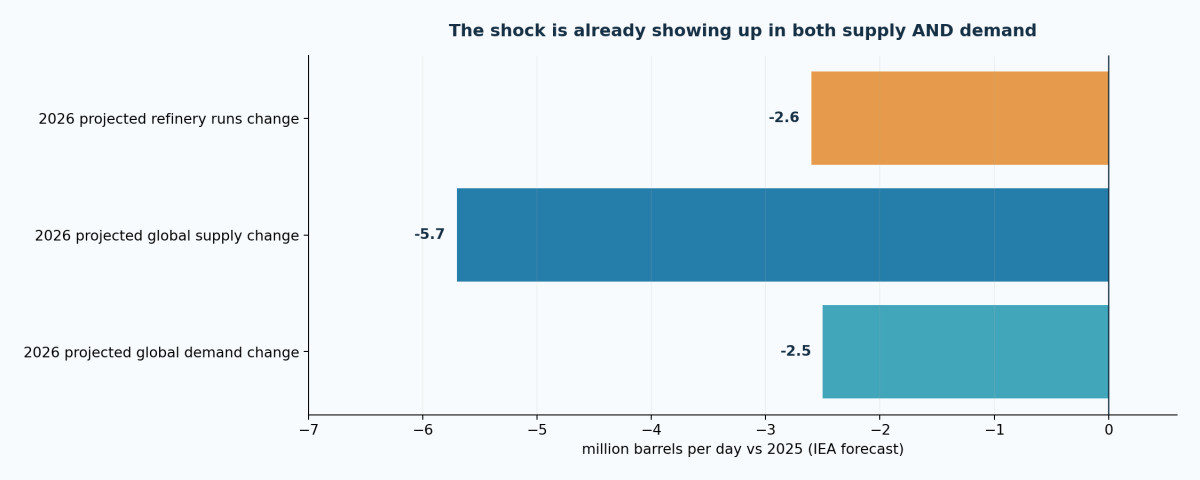
Figure 1. IEA September 2026 forecast. World supply is projected to average 5.7 million barrels per day below 2025, demand 2.5 million barrels per day below 2025, and refinery throughput 2.6 million barrels per day below 2025. These are separate annual forecasts, not quantities to add together. [1]
The question is no longer simply who controls the next oil field.
It is who can produce the barrel, refine it, transport it, insure it, finance it, purchase it, and absorb the cost of making it available.
Then we need to ask who owns those cash flows, where the capital goes, what happens to inflation and debt, and whether the pressure eventually becomes large enough to force another monetary intervention.
Because the next liquidity crisis may begin somewhere that does not initially look like a financial market.
It may begin with the price of moving a barrel of diesel.
01 · THE ORIGINAL FRAMEWORK
Go Back to Venezuela, Iran and Cuba. That Is Where This Started.
I want to establish something before we go any further.
This article did not begin with the latest oil-price movement. It did not begin when somebody published another headline about a refinery in Russia. It did not begin when the Federal Reserve raised rates last week.
For me, this began with the larger geopolitical sequence I was already examining: Venezuela, Iran, Cuba, and the possibility of a subsequent development connected to China and the wider structure of global economic power.
My January research was looking at several kinds of pressure simultaneously.
In Iran, I was watching currency stress, protests, information restrictions, state repression, external military options, diplomatic withdrawals, airspace closures and regional force posture.
In Venezuela, I was watching the shift from sanctions, maritime pressure and military positioning toward direct American intervention and a possible restructuring of control over the country's enormous petroleum resources.
In Cuba, I was watching energy access, sanctions, the deterioration of public infrastructure and the possibility that prolonged economic pressure could produce a political transition without a conventional invasion.
And behind those developments was China, because China connects the Iranian oil market, Russian energy exports, Venezuelan investment history, manufacturing, international shipping, dollar settlement and the alternative commercial arrangements governments are trying to develop.
These countries are not identical.
They do not have the same military capabilities, economic resources, population, geography or internal political structure.
The connection I was tracing was not ideological similarity.
The connection was energy access and the ability to control or disrupt the infrastructure through which an economy operates.
What I wrote in January
On January 2, I published The Middle East Fragmentation Regime. The framework was already broader than Iran. It included Yemen, the Red Sea, Gulf relations, Israel, Iran, regional shipping and the possibility that separate conflicts would amplify one another.
On January 3, Iran at the Edge examined currency deterioration, protests and external pressure.
On January 12, The Iran Decision Window treated reported military, cyber and psychological options as evidence of an active decision process, not confirmation that a strike order had been issued.
On January 14, Iran's Decision Window expanded that approach into observable indicators: embassies, airspace, base protection, shipping and retaliation risk.
Those pieces matter because they establish the framework before the February 28 escalation. They do not make every subsequent development an automatic confirmation of every possible scenario I discussed.
Venezuela changed the Western Hemisphere energy map
Venezuela has enormous petroleum resources, including heavy and extra-heavy crude that has a particular relationship with the American Gulf Coast refining system.
The United States produces extraordinary quantities of light crude from shale formations. But some American refineries were built and upgraded to handle heavier, more sulfur-rich feedstocks.
That means being the world's largest crude producer does not eliminate the commercial value of imported Venezuelan heavy crude.
Venezuela also requires enormous investment in electricity, wells, processing, transportation, export terminals and maintenance.
It is not enough to control a resource on paper.
You have to make the system underneath that resource function.
Iran became the chokepoint war
Iran was a different problem from the beginning.
Its importance does not depend solely on how much Iranian crude reaches the market. The geography around Iran affects exports from multiple Gulf producers.
Once the Strait of Hormuz becomes commercially impaired, the conflict touches the petroleum trade of countries that are not Iran.
That is why the March research moved from military headlines into shipping, commercial insurance, inventory timing and global monetary transmission.
Cuba became the prolonged infrastructure crisis
Cuba did not follow the fast sequence I originally considered.
Instead, restrictions on fuel access and severe domestic infrastructure problems have produced a prolonged electricity and economic crisis.
The timetable changed.
The underlying question did not: what happens to a country when it cannot reliably obtain the energy necessary to operate its electricity grid, transportation, water systems, refrigeration and industrial equipment?
The later part of the chain remains open
I identified another possible development in the original framework without fully publishing that scenario.
I am leaving it open now.
The Trump–Xi meeting this week is an observable checkpoint, but its existence does not establish the outcome of a later geopolitical event.
I am not going to rewrite the January research to make every subsequent event look inevitable.
The value of a causal framework is that we can follow it as new information arrives, including information that changes or weakens the original path.
Original framework: Venezuela changes the Western Hemisphere resource and ownership map. Iran exposes the global chokepoint system. Cuba demonstrates the consequences of prolonged energy and infrastructure failure. China connects the commodity, trade, currency and industrial dimensions.
02 · RUSSIA AND UKRAINE
Ukraine Is Striking the Conversion Machine, Not Just Russian Oil.
Now move from the original framework into what is happening today.
Ukraine continues striking Russian oil refineries and petroleum infrastructure.
The average person sees another refinery headline and interprets it primarily as damage to Russia's ability to finance and sustain its war.
That is one consequence.
It is not the complete economic consequence.
Crude oil sitting in the ground is not diesel at a farm, gasoline at a station, jet fuel at an airport or marine fuel loaded at a port.
The crude must be produced, transported, refined, blended, stored and delivered.
A refinery is not simply a tank where crude enters one side and gasoline exits the other. It is a complex arrangement of distillation units, catalytic crackers, hydrocrackers, desulfurization equipment, hydrogen systems, utilities, storage tanks and product-blending operations.
Damage to one critical unit may affect product yields even when portions of the refinery continue operating.
A plant can remain physically present while producing substantially less diesel.
A refinery can restart crude processing before every downstream conversion unit is repaired.
Repairing specialized industrial equipment is not always a matter of purchasing an ordinary replacement part. Sanctions, component availability, specialized labor, engineering requirements and repeated attacks can lengthen the recovery period.
What the September reporting established
Reuters reported on September 15 that three of Russia's six largest diesel-producing refineries had significantly reduced or stopped production following drone attacks. Those six facilities collectively accounted for approximately half of Russian diesel production. Reuters reported that Kirishi had shut, while Volgograd and NORSI were operating at about one-quarter of their nameplate capacity. [2]
That does not mean half of Russia's entire refining industry permanently disappeared.
It means a group of facilities important to diesel production had suffered serious disruptions.
The difference matters.
The IEA also reported that a Russian refinery was successfully struck, on average, approximately once every three days during the first eight months of 2026. [2]
Repeated attacks can create a second-order problem even when individual plants restart.
Repair crews are repeatedly redirected.
Spare parts become more valuable.
Operators must decide which processing units can run safely.
Domestic fuel demand competes with exports.
And traders become less confident that the next contracted cargo will actually be available.
The export system does not simply stop everywhere
There is an important qualification here.
Russia has restricted exports of several petroleum products, but exemptions and regional commercial relationships continue to matter.
Reuters reported that Russian diesel deliveries to parts of Central Asia increased in August under exemptions from broader export restrictions. [8]
That means the correct variable is not a fictional switch labeled "Russian diesel exports: on/off."
We need to follow the actual flow ledger: which products, which grades, which destinations, which refineries, and which restrictions.
Ukraine's military objective and the global market effect are different questions
Ukraine describes Russian petroleum infrastructure as part of the economic and logistical system sustaining Russia's invasion. Russia has continued striking Ukraine's own energy infrastructure, with the United Nations documenting extensive damage and civilian consequences. [9]
Those are separate military and humanitarian issues.
The global-market connection is that damaged refining capacity cannot simultaneously provide the diesel another region needs during a different conflict.
And that brings us directly to Iran.
03 · THE GLOBAL DIESEL SYSTEM
Two Different Wars Are Meeting in the Same Diesel Market.
This is why I am not writing a Russia article and stapling an Iran article to it.
The wars interact in the physical fuel system.
According to the IEA's September Oil Market Report, combined net exports of diesel and gasoil from Gulf countries and Russia were 1.6 million barrels per day lower in August than in February.
Before the crisis, those exporters together accounted for almost 45% of global seaborne diesel and gasoil trade. [1]
That is an extraordinary concentration of globally traded middle distillates exposed to simultaneous disruption.
The Gulf's own net diesel and gasoil exports averaged approximately 390,000 barrels per day in August, just over one-quarter of their prewar level. [1]
A refinery elsewhere can respond by processing more crude.
But only if the refinery has the right capacity, crude grade, product yield, operating reliability, shipping access and financing.
And refineries were already operating in an abnormal environment.
The IEA reported that global refinery throughput reached 81.4 million barrels per day in August, still 4.2 million barrels per day below the previous year's level. [1]
The Atlantic Basin's refining margins reached record levels, led by diesel.
That is the financial consequence of a physical conversion bottleneck.
A barrel is not interchangeable with every other barrel
This deserves emphasis because people routinely discuss oil as though all barrels are identical.
A heavy sour crude barrel is not the same refinery input as a light sweet barrel.
A refinery optimized for one feedstock may face a lower product yield or higher processing cost with another.
Diesel specifications vary across regions.
Marine fuels have sulfur requirements.
Seasonal gasoline blending changes.
A product may exist somewhere in the world but be too expensive to transport to the market that needs it.
This is why a large crude producer can still experience diesel scarcity.
Diesel is the physical economy
Diesel operates trucks, tractors, combines, excavators, generators, heavy construction machinery, mining equipment, and substantial portions of freight and industrial transportation.
When diesel becomes expensive, the impact moves into the prices of physical goods.
A farmer pays more to plant and harvest.
A trucker pays more to move freight.
A contractor pays more to operate equipment.
A distributor pays more to deliver food.
A manufacturer pays more to receive components and ship finished products.
Eventually those costs reach the household.
That is why I am watching the diesel market more closely than the daily headline movement in Brent.
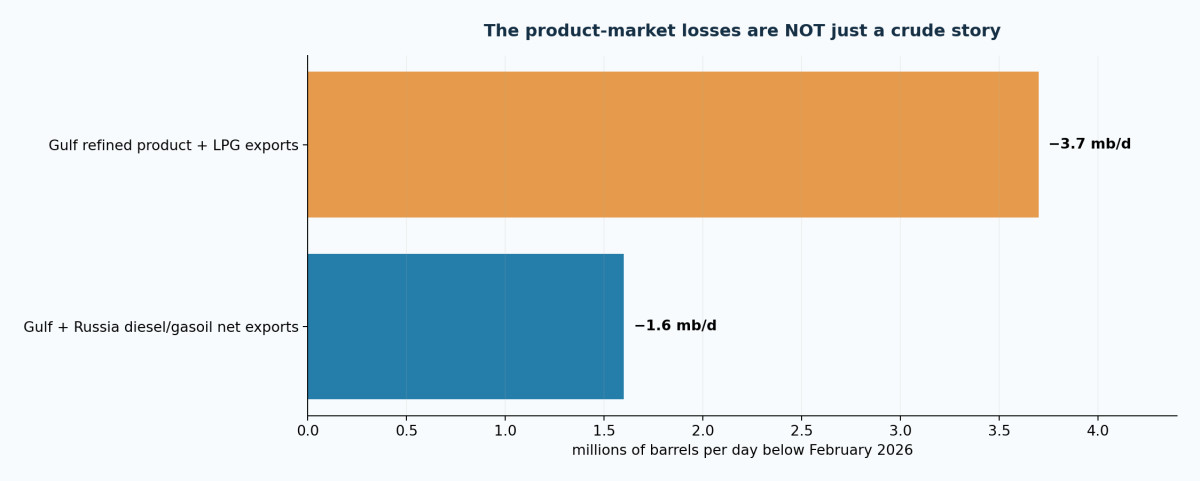
Figure 2. IEA September report: Gulf refined-product/LPG losses and combined Russian/Gulf diesel-gasoil losses. The categories overlap and must not be added together. [1]
Washington's incentives are not uniform
The idea that every damaged Russian refinery automatically benefits the United States fails when we examine who pays American diesel prices.
Reuters reported on September 15 that Trump had publicly urged Ukraine to stop striking Russian diesel infrastructure because the attacks were contributing to global fuel shortages. The Financial Times subsequently reported further pressure on Zelenskyy regarding refinery attacks. [2][10]
That is important evidence.
Higher international petroleum prices can benefit American producers while higher American diesel prices damage agriculture, transport and household finances.
The same administration can have an interest in supporting its domestic energy industry and an interest in reducing the consumer consequences of disrupted foreign fuel supplies.
Those are competing objectives inside the same economy.
We need to preserve both if we want to understand what is actually happening.
04 · HORMUZ
The Strait of Hormuz Is Not a Light Switch.
I made this argument in March, and the subsequent data have given us a much better view of the operating mechanics.
People describe Hormuz as open or closed.
That is useful for a headline.
It is inadequate for commercial analysis.
A tanker may be physically capable of transiting a waterway while the commercial conditions surrounding the transit remain severely impaired.
Shipping companies have to consider military risk, insurance coverage, crews, possible escorts, route availability, port conditions, contract terms and financing.
An insured cargo is not the same as an uninsurable cargo.
A cargo arriving tomorrow is not the same as a cargo arriving in three weeks.
A tanker tied up in an improvised transfer system is not simultaneously available to complete another voyage.
What the IEA reported
In August, total oil exports from Gulf countries were estimated at approximately 13 million barrels per day, nearly half their prewar level.
Refined-product and LPG exports were about 3.7 million barrels per day below February, a decline approaching 60%. [1]
That reduction is not equivalent to all oil production in the Gulf disappearing.
It describes export and product-flow constraints.
The distinction is exactly why I have been discussing corridors and timed failure instead of only production numbers.
The Oman transfer system
Reuters reported on September 21 that ship-to-ship crude transfers near Oman had increased to approximately 2.5 million barrels per day in September, compared with about 1.4 million in August.
In some trades, very large crude-carrier freight costs had exceeded $30 per barrel. [11]
That is the market creating an alternative route through commercial adaptation.
It is also evidence that the normal system has not been restored.
The workaround uses vessels, time, insurance and additional handling.
The extra cost eventually has to be absorbed somewhere.
The producer may accept a lower netback.
The refinery may pay more for delivered crude.
The trader may use additional working capital.
The consumer may face a higher product price.
Someone pays.
And it is not necessarily the person who ordered the cargo.
05 · REDUNDANCY AND CHOKEPOINTS
What Happens When the Alternative Route Becomes a Target?
This is another development that deserves more attention than a passing headline.
Saudi Arabia's East–West pipeline allows crude to move from the Gulf side of the country to the Red Sea without passing through the Strait of Hormuz.
It has therefore become much more important during the conflict.
Reuters reported that the pipeline had been carrying approximately 4 million to 5 million barrels per day, representing roughly 4%–5% of global oil supply.
On September 17, Reuters reported that three pumping stations had been damaged in an attack, with repair estimates varying among industry sources. [3]
That is what I mean when I say redundancy is not the same thing as unlimited replacement capacity.
If Hormuz becomes difficult, use the pipeline.
If the pipeline becomes difficult, increase transfers and alternative shipping.
If tanker availability becomes scarce, pay more for ships.
If the Red Sea becomes difficult, reroute farther.
Each solution consumes capacity elsewhere in the system.
The alternative route becomes more valuable precisely because the original route is impaired.
That increased value also makes the alternative route a more consequential point of failure.
Bab el-Mandeb and the Houthi dimension
The Red Sea is not a frictionless escape route.
Ships using it must consider the security environment around Bab el-Mandeb, the Gulf of Aden and the Suez route.
A longer route around southern Africa increases voyage time.
Longer voyages consume tanker-days.
More tanker-days raise the amount of freight capacity required to deliver the same monthly volume.
Higher freight costs increase the landed price.
This is why the Houthis, Iran, Saudi Arabia, Oman, Egypt and international shipping markets belong in the same article.
They affect different pieces of the route.
A country can possess enormous oil reserves and still have trouble delivering those reserves into the market that needs them.
That is corridor power.
And it is the reason my March 29 article, The Clock Starts at Hormuz, treated the system as a stress map rather than an ordinary map of trade volumes.
06 · INVENTORIES
The Inventory Clock Has Started Showing Up in the Official Data.
In March I called it the inventory clock.
In June I expanded that into the oil cushion.
In August I published the longer inventory reconstruction.
The argument was never that the planet was about to consume its final barrel of crude oil.
It was that inventory buys time, and different inventories buy different kinds of time.
Commercial crude is refinery feedstock.
Stored diesel is usable fuel.
Strategic crude requires release authorization and a logistical path to the appropriate refinery.
Oil sitting on a tanker is not necessarily available at the depot where a trucking company needs fuel tomorrow.
And a wrong-grade barrel does not become the right-grade barrel because a financial market says both belong to the same commodity category.
The September inventory report
The IEA reported a further 95-million-barrel decline in global observed inventories during August.
That brought cumulative draws since February to approximately 507 million barrels, an average draw of 2.8 million barrels per day. [1]
That is the system using stored supply to bridge a prolonged disruption.
The world is adapting through production elsewhere, additional refinery throughput, route changes, inventory releases and reduced consumption.
But an inventory draw is not the same thing as sustainable new flow.
A warehouse can deliver today's order from yesterday's stored goods.
It cannot indefinitely replace a manufacturing plant that remains offline.
The United States is consuming part of its public buffer
The EIA's weekly Strategic Petroleum Reserve series records approximately 413.325 million barrels on April 3 and 284.957 million barrels on September 11.
That is a reduction of approximately 128.4 million barrels between those observations. [12]
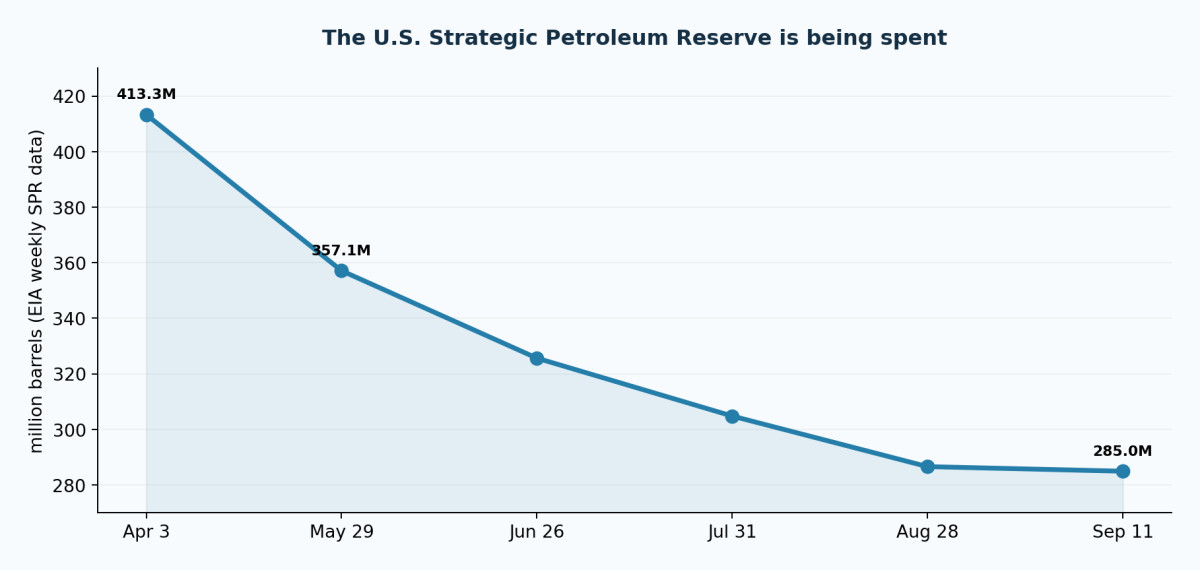
Figure 3. EIA weekly SPR ending stocks. The approximately 128.4-million-barrel reduction is a change in the American public emergency stock between the specified observations, not an estimate of total global production lost. [12]
This creates another distributional question.
The government releases public inventory.
Refiners receive additional feedstock.
Consumers may receive some price relief.
Private producers continue selling into the prevailing market.
The public emergency buffer becomes smaller.
That does not mean the release is economically irrational. It may be useful in a severe disruption.
It means the costs and benefits appear on different balance sheets.
The replenishment problem
An emergency reserve is most valuable when there is a credible way to refill it afterward.
Replacing crude at lower prices can be favorable.
Replacing it during continued global scarcity can be expensive.
Delaying replenishment preserves cash today but maintains a smaller emergency buffer.
The SPR is therefore part of the current market and part of the next emergency's starting conditions.
Demand destruction is not recovery
The IEA forecasts that global oil demand will average 2.5 million barrels per day less in 2026 than in 2025.
That is a forecasted year-on-year change, not a declaration that the entire reduction represents permanently unavailable physical supply. [1]
Some of it is demand destruction.
Households reduce consumption because fuel is too expensive.
Companies reduce freight because sales are weaker.
Factories cut production.
Importing countries run into financing constraints.
Oil prices can fall because the economy is consuming less, even while the original physical damage remains.
That is not the same thing as a healthy, fully restored energy market.
07 · THE AMERICAN ENERGY MACHINE
The United States Is Not the Petrodollar Country It Was in the 1970s.
Now we get to the part that initially sounds contradictory.
The United States used to be much more dependent on imported crude.
Today it produces more crude oil than any other country.
EIA reports that American crude production averaged a record 13.6 million barrels per day in 2025, the eighth consecutive year the United States held the number-one producer position. [6]
That does not mean the United States has a literal monopoly on world oil production.
Russia, Saudi Arabia and numerous other countries remain major producers.
It does not mean America has stopped importing crude.
It means the United States occupies a different position in the global energy system than it did several decades ago.
The old petrodollar structure
People usually explain the petrodollar like this: oil-producing countries sell petroleum in dollars and recycle their surplus dollars into American financial assets.
That captures part of the structure.
The broader system involves oil invoicing, reserve management, dollar bank credit, trade finance, American military relationships, Treasury-market depth and the investment of export earnings into global financial assets.
Oil was never a formal commodity backing the dollar.
The connection was commercial and institutional.
A global commodity priced and financed heavily in dollars reinforces demand for the currency and the financial system behind it.
The modern United States sits on more sides of the transaction
Today, America may produce the barrel.
It may refine the barrel.
It may export the diesel.
It may export the LNG.
It may provide the drilling equipment.
It may supply the engineers rebuilding a foreign power grid.
It may finance the pipeline.
It may insure the cargo.
It may provide the derivatives used to hedge the price.
And the earnings may enter American-listed companies, banks, funds, pension portfolios, private equity vehicles, energy-producing states and tax systems.
That is the evolution I examined in The Petrodollar Did Not Die. It Mutated Into the Commodity Dollar.
The United States is no longer merely the issuer of a widely used settlement currency.
It is also a major owner and operator of the physical commodity system.
Foreign disruption can increase the relative value of American capacity
Imagine three refineries supplying the same marginal diesel market.
One refinery is damaged in Russia.
Another refinery cannot export normally from the Gulf.
The third refinery is operating in the United States.
The third refinery has not magically become more productive.
Its available output has become more valuable relative to constrained competing supply.
That is one reason refinery margins can widen during an international product shortage.
The same concept applies to American crude production, LNG exports, pipelines, storage, marine terminals and energy services.
Disruption elsewhere can increase the strategic and commercial value of reliable American capacity.
But America still pays globally connected prices
This is where the simplistic version of the argument fails.
The American consumer does not live inside a separate American oil market.
American oil and refined products remain connected to international trade.
Higher global petroleum prices can benefit American producers while increasing costs for American consumers.
A Texas producer may receive a higher price.
An Illinois trucking company may pay more for diesel.
A Gulf Coast refiner may earn more from scarce products.
A family may pay more for groceries and transport.
A shareholder may receive a larger dividend.
A contractor may postpone buying equipment.
All those outcomes can occur simultaneously.
The correct concept is distribution, not an automatic national gain.
And to understand that distribution, we have to follow ownership.
08 · VENEZUELA
Venezuela Is More Than an Oil Agreement. It Is an Ownership and Infrastructure Buildout.
Look closely at what Washington and Caracas announced at the end of August.
The White House and Department of Energy describe a new arrangement giving the United States significant economic and governance rights connected to an estimated 65 billion barrels of Venezuelan proven reserves.
The arrangement involves 17 fields and North American Blue Energy Partners, or NABEP. [5][13]
Reuters reported that NABEP was granted a long-term lease structure, with the U.S. government receiving a 35% equity stake in the company's corporate parent through the Pentagon's Office of Strategic Capital. The reported terms also provide a guaranteed portion of production and preferential purchase rights over additional output. [37]
The details of ownership, Venezuelan law, governance, taxation and contract durability remain material.
These are not minor issues.
Legal experts and industry participants have raised questions about the structure and transparency of the agreement. [38]
But the economic scale of the proposed arrangement makes it important to the broader framework.
Sixty-five billion barrels underground are not sixty-five billion barrels available for export
The IEA estimated Venezuela's August production at approximately 1.16 million barrels per day. [1]
That is the current-flow starting point.
Recovering additional output requires wells, equipment, diluent, power, pipelines, export terminals, skilled labor, financing and long-term contractual stability.
A resource can be enormously valuable while remaining difficult to produce at scale.
That is why I separate reserves, production capacity, actual output and exports.
The heavy-crude relationship matters
Venezuelan crude has a specific relationship with parts of the American Gulf Coast refining system.
American shale production is heavily weighted toward lighter crude.
Some Gulf Coast refineries have significant investments in equipment designed to process heavier and more sulfur-rich grades.
Venezuelan heavy crude can therefore complement American light-crude production rather than simply replace it.
That creates a commercial opportunity beyond the headline size of the reserves.
More appropriate feedstock can improve refinery utilization and product economics, subject to transport, sanctions, pricing and plant configuration.
The electricity agreements are part of the oil deal
On September 2, DOE announced agreements involving Chevron, Eni and GE Vernova to expand petroleum activity and modernize Venezuela's electricity infrastructure. [13]
Why does an oil article need to discuss electricity?
Because wells need pumps.
Pipelines need pumps.
Upgraders need power.
Ports need power.
Processing plants need power.
Communications and control systems need power.
A country can possess gigantic oil resources and still underproduce if its electric grid cannot reliably support the industrial system.
Venezuela's petroleum recovery is therefore partly an electricity reconstruction problem.
American companies can earn revenue before major new oil volumes arrive
Chevron can expand petroleum operations.
Eni can participate in long-term development.
GE Vernova can provide generation and grid equipment.
Halliburton and other service companies can participate in drilling, well rehabilitation and project development.
Those activities create economic flows before a major increase in export capacity appears in the data.
That is important to the ownership thesis.
The return from a resource-development project does not belong exclusively to whoever eventually sells the crude.
Engineering firms, equipment manufacturers, banks, insurers, service providers and shareholders can participate throughout the buildout.
Now place Venezuela beside Russia and Iran
I am not claiming that Ukrainian refinery strikes and the Iran conflict mechanically caused the Venezuela agreement.
Venezuela has its own political, legal and industrial history.
But disrupted supply elsewhere can increase the relative strategic value of accessible Western Hemisphere resources.
That is the intersection.
A country can gain influence through ownership arrangements, commercial access and infrastructure investment without immediately producing millions of additional barrels.
That is why the Venezuelan buildout is central to the economic-machine argument.
09 · CUBA
Cuba Shows What Energy Access Means After the Lights Go Out.
Cuba has not followed the quick progression I initially considered.
Instead, it remains inside a prolonged economic and infrastructure crisis.
On September 18, Cuba suffered another nationwide electricity-system collapse.
Associated Press reporting described widespread disruption to electricity, transportation, water access, food preparation and communications. The country's power system has experienced repeated failures amid fuel scarcity, deteriorated generating equipment and severe economic constraints. [4]
U.S. energy restrictions have further constrained fuel deliveries and access to necessary equipment.
Cuba's own maintenance failures, aging plants, financial limitations and economic-management problems are also part of the explanation.
Removing one factor would not automatically repair the others.
What I mean by an energy blockade
When I describe Cuba's situation as an energy blockade, I am discussing the effect of restrictions that severely constrain fuel deliveries and the commercial relationships needed to maintain energy infrastructure.
I am not asserting that every Cuban port is physically surrounded by a continuous ring of American warships.
That distinction matters because the mechanism matters.
Sanctions, secondary sanctions, shipping restrictions, payment difficulties, insurance concerns and reduced fuel availability can impose enormous pressure without a conventional amphibious operation.
Electricity is the infrastructure underneath other infrastructure
When electricity fails, water pumps can fail.
Wastewater systems can be disrupted.
Refrigeration becomes unreliable.
Hospitals depend on backup generation.
Communications become harder.
Businesses lose operating hours.
Factories cannot maintain production.
Workers lose income.
Tax revenue weakens.
Maintenance becomes more difficult to finance.
And the next outage arrives in a system with fewer reserves than the previous one.
That is a negative feedback loop turning into a reinforcing deterioration cycle.
Cuba also raises the future ownership question
If a major political or economic transition eventually occurs, who finances the reconstruction?
Who supplies the power plants?
Who restores the grid?
Who owns the ports, telecom systems, logistics facilities and fuel contracts?
Who provides financing?
What rights do Cuban citizens and institutions retain over the assets?
Those are conditional questions, not a claim that a transfer of Cuban assets has already been agreed.
They are the same category of questions I have been asking about Venezuela.
The difference is that Venezuela has announced a major petroleum-development structure while Cuba remains in an acute infrastructure crisis.
That is where the original sequence stands today.
10 · CHINA
This Week's Trump–Xi Meeting Sits at the Intersection of the Entire System.
China's Foreign Ministry announced that Xi Jinping will visit the United States from September 23 through September 25.
As of this article's September 21 research cutoff, the outcome of that visit is unknown. [16]
I am watching the meeting because China touches almost every branch of the framework.
China is a major energy importer.
China is a major industrial exporter.
China purchases Russian petroleum and gas.
China has been a major buyer of Iranian crude.
China possesses substantial refining capacity.
China depends on international shipping.
China operates inside the dollar system while developing alternative settlement arrangements.
China has extensive industrial and financial relationships with the United States.
And China has substantial influence over critical-mineral and manufacturing supply chains that matter to energy, defense and AI infrastructure.
Iranian oil has a different role for Beijing
For Washington, Iranian oil is connected to sanctions, regional security and strategic leverage.
For Chinese buyers, Iranian crude may offer supply diversification and a discount reflecting sanctions or trading restrictions.
That apparent advantage depends on the ability to deliver the cargo.
A discounted barrel that cannot be shipped, insured or financed normally is not necessarily an economically attractive barrel.
The discount must compensate for the entire risk and delivery cost.
Russian energy is the second leg
Russia has redirected significant energy trade toward Asia since its full-scale invasion of Ukraine.
China can benefit from access to discounted Russian crude or long-term pipeline supply.
At the same time, disruptions to Russian refining can contribute to higher global product prices.
China's own refineries may capture some of the opportunity created by diesel scarcity elsewhere, but their output depends on crude sourcing, plant capacity, domestic demand and export policy.
China can therefore be a buyer benefiting from discounted feedstock and a major industrial economy exposed to higher international fuel and freight costs at the same time.
Sanctions are not just barriers. They redirect flows.
A sanction may prevent a transaction.
It may also redirect a transaction through another intermediary.
A license may permit a limited category of trade.
A tariff can change which importer remains commercially competitive.
A country may accept a discount to preserve sales.
Another country may pay more to replace the supply it can no longer purchase.
That is why I connect sanctions policy to physical cargo flows instead of treating every sanction announcement as an isolated political statement.
The commercial consequences of the meeting
I want to see whether the meeting produces changes in actual energy purchases, commercial licenses, tariffs, rare-earth restrictions, industrial access or diplomatic arrangements affecting Russia and Iran.
I want to see whether China increases purchases of American oil or LNG.
I want to see whether Chinese purchases of Iranian or Russian energy change.
I want to see whether any agreement alters the financing or insurance environment around commodity trade.
And I want to see whether the meeting changes the use of scarce American military and industrial resources across the Gulf and Pacific theaters.
Those are observable questions.
A joint statement without changes in cargoes, contracts, licenses or enforcement may have a limited effect on the physical system.
A commercial agreement changing actual supply flows could have a much larger effect.
That is why the meeting matters to this research without requiring me to invent the outcome beforehand.
11 · LNG
The Oil War Also Has a Natural-Gas and LNG Layer.
I do not want readers to finish this article thinking the entire issue is liquid petroleum.
The Gulf is also central to global LNG trade.
Qatar is one of the world's major LNG exporters, and the Strait of Hormuz matters to its commercial access.
The conflict has also damaged parts of Qatar's LNG infrastructure.
Reuters reported on September 21 that QatarEnergy faced possible delays to LNG expansion projects because of the Hormuz crisis, damaged facilities and disrupted equipment deliveries. [39]
That matters to electricity generation, industrial production, petrochemicals and fertilizer.
Natural gas connects directly to the food system
Ammonia production depends heavily on natural gas, both as a feedstock and energy source.
Ammonia is a core input into nitrogen fertilizer.
A natural-gas disruption can therefore affect fertilizer economics before the consumer sees the final food-price effect.
Crop-input decisions can occur months before harvest.
That creates a delay between the energy shock and the agricultural consequences.
The American LNG channel
When Gulf LNG becomes harder to obtain, alternative supply becomes more commercially valuable.
North American LNG projects may attract additional demand, investment or long-term contracting interest.
There is a particularly revealing ownership relationship here.
QatarEnergy itself is a partner with ExxonMobil in the Golden Pass LNG project in Texas.
A Gulf producer exposed to disruption at home can simultaneously participate in energy-export infrastructure in the United States.
That is a direct example of why the modern financial and physical energy system does not divide neatly according to national flags.
Capital can own multiple sides of the same energy trade.
That is the ownership layer again.
12 · THE WEALTH TRANSFER
An Oil Shock Redistributes Purchasing Power Before It Destroys Demand.
This is probably the most important economic distinction in the article.
People hear that energy prices are rising and talk about the economy as though everyone experiences the same loss.
They do not.
A household pays more for gasoline.
A trucking company pays more for diesel.
A farmer pays more for fuel and fertilizer.
A manufacturer pays more for freight and energy.
Part of that additional spending becomes revenue somewhere else.
The producer receives a higher realized price.
The refiner may receive a wider product margin.
The tanker owner may receive a higher freight rate.
The insurer may receive a war-risk premium.
The commodity trader may profit from physical arbitrage or price volatility.
The pipeline owner may benefit from additional throughput, subject to capacity and contract terms.
The shareholder may receive stronger earnings or a higher valuation.
The government may collect more royalties or tax revenue.
The oil shock transfers purchasing power before it destroys purchasing power.
That is the mechanism.
It is not a universal benefit even within the energy industry
A crude producer may benefit from higher prices if production is maintained.
A refiner may benefit from a wider diesel spread if it can obtain crude and continue operating.
Another refiner may lose money because its feedstock becomes inaccessible.
A pipeline may benefit from utilization.
Another pipeline may be physically damaged.
An LNG producer may gain customers.
Another LNG producer may face a prolonged outage.
Even the energy industry is not one balance sheet.
The second stage is behavioral change
Higher energy costs eventually alter consumption and investment.
The household drives less.
The trucking company increases freight rates.
The business delays equipment purchases.
The airline changes routes or pricing.
The manufacturer cuts production.
The farmer adjusts input decisions when possible.
Importing countries conserve foreign exchange or restrict consumption.
That is demand destruction.
Demand destruction may bring down oil prices.
But a lower oil price caused by collapsing activity is not equivalent to a lower oil price caused by abundant and reliable supply.
A nominal gain can coexist with a real loss
Energy-sector revenue can rise in nominal dollars.
Corporate profits can rise in particular industries.
Nominal tax receipts can increase.
Nominal GDP can receive price-driven support.
Meanwhile, real household purchasing power may decline.
Those facts do not contradict one another.
They describe different measures.
This distinction becomes essential when we reach the national debt.
13 · OWNERSHIP AND POLICY
Yes, Public Officials Own Energy Assets. Follow the Disclosures.
Now I want to discuss the part of this economic structure that should not be ignored simply because it is uncomfortable.
Some of the people participating in energy, sanctions, fiscal and military policy also have financial exposure to the businesses affected by those decisions.
That is a documented ownership question.
It is not automatic proof that someone began or prolonged a war for personal gain.
Those are different claims, and I am not going to combine them.
Trump's disclosed portfolio
CBS News reviewed President Trump's Office of Government Ethics disclosures through the second quarter of 2026.
CBS reported that the President's investment accounts continued buying and selling oil and natural-gas securities during the Iran conflict, including periods of fighting, ceasefire and renewed hostilities. [18]
The President's overall portfolio is extensive.
CBS reported approximately 3,600 securities transactions in the first quarter, with disclosed transaction ranges totaling roughly $212 million to $695 million.
Energy holdings were only one portion of that portfolio.
That distinction matters because not every transaction in a broadly managed portfolio represents a targeted geopolitical trade.
The Joint Economic Committee estimate
Democratic staff on the congressional Joint Economic Committee analyzed Trump's energy holdings using disclosed positions and market prices.
They estimated that the value of the President's oil-and-gas holdings increased from a reported range of approximately $13 million–$46 million at the beginning of 2026 to approximately $17 million–$61 million by mid-August.
Their comparison of maximum reported values produced an estimated increase of up to $15.5 million. [19]
That is a committee-minority estimate.
It is not an audited personal trading-profit statement.
The underlying financial disclosures use value ranges rather than exact amounts, and a comparison of disclosed holdings can be affected by subsequent transactions.
The estimate is still relevant to the ownership question.
It shows the financial exposure associated with a significant energy portfolio during a period of extraordinary market volatility.
The April 7 ExxonMobil transaction
CBS identified a particularly important disclosed transaction.
On April 7, Trump's investment accounts sold between $500,000 and $1 million of ExxonMobil shares.
Later that evening, Trump announced a ceasefire in the Iran conflict.
CBS reported that ExxonMobil opened approximately 6.5% lower the following day. [18]
That is a real transaction and a real chronology.
It is not proof that Trump personally ordered the sale based on advance knowledge of the announcement.
The White House says he did not direct the timing of individual transactions.
The White House's explanation
According to CBS, the White House says independent third-party financial institutions manage Trump's stock and bond portfolio through discretionary accounts using computer-based model portfolios designed to replicate recognized indexes.
The White House says neither Trump nor his family directs the timing of individual purchases or sales.
CBS also reported that investment professionals viewed parts of the broad trading activity as consistent with direct indexing and tax-loss harvesting. [18]
That explanation belongs in the article.
It is possible for a beneficial owner to have real financial exposure without personally directing a particular transaction.
Those are separate facts.
Trump personally, the portfolio, and the Trump Organization are not interchangeable
I want to be particularly precise here because the ownership analysis becomes unreliable if we collapse distinct legal and financial entities into one category.
A security reported in Trump's personal financial disclosures is not automatically a purchase made by the Trump Organization.
A business investment made by a Trump-controlled entity is not automatically a transaction in the President's publicly disclosed stock portfolio.
A government agreement involving Venezuela is not, by itself, evidence that a privately owned Trump business holds an undisclosed interest in the arrangement.
To attribute a particular investment to the Trump Organization, we would need the company, ownership record, filing or transaction document establishing that connection.
The verified evidence discussed here concerns the President's reported financial holdings and his accounts' transactions. [18][19]
That is substantial enough to analyze without inventing an additional corporate transaction.
Members of Congress
Congressional periodic transaction reports provide another avenue for examining financial exposure.
Under the STOCK Act disclosure framework, covered transactions above $1,000 generally must be reported within 30 days after notification and no later than 45 days after the transaction. [23]
That creates a significant timing distinction.
The trade date is not necessarily the public disclosure date.
A filing appearing after an attack does not establish that the trade occurred after the attack.
A purchase occurring before an attack does not, by itself, establish advance knowledge.
Those are basic rules for interpreting the data.
Public congressional-trading trackers include reported energy-company transactions involving members of both parties, including Senator John Boozman and Representative Gilbert Cisneros. The original article's examples include a reported Chevron purchase by Boozman and reported EOG Resources and Occidental purchases by Cisneros. Other disclosures include sales. [20][21][22][36]
These tracker records are leads for a formal audit, not substitutes for the underlying official periodic transaction reports.
I am preserving purchases and sales because deleting transactions that do not fit a thesis would manufacture a pattern.
What a serious transaction audit needs to establish
| Variable | Why it matters |
|---|---|
| Beneficial owner | Identifies who ultimately has the financial exposure. |
| Actual trade date | Establishes chronology relative to public events. |
| Disclosure date | Shows when the public learned about the transaction. |
| Security and direction | Separates purchases from sales and specific firms from broad indexes. |
| Reported value range | Prevents a disclosure band from being misrepresented as an exact amount. |
| Policy or committee authority | Identifies potential overlap between financial exposure and public responsibilities. |
| Information access | Would be necessary for any stronger allegation involving nonpublic knowledge. |
| Investment discretion | Distinguishes personal trading instructions from independently managed accounts. |
Corporate insiders are another category
MarketWatch reported on September 21 that insiders at more than 35 energy companies had purchased roughly $55 million in shares of their companies. [24]
Corporate insiders are not the same as elected officials.
Their information, authority, legal responsibilities and incentives differ.
But their transactions can illuminate how people operating inside energy businesses assess future earnings and valuations during geopolitical uncertainty.
The conclusion supported by the record
The documented overlap is between public policy authority, beneficial ownership, market volatility and company earnings.
The record discussed here does not independently prove that a particular official chose war, a ceasefire, an SPR release or a sanction to enrich themselves.
It also does not establish that every disclosed trade was profitable.
The structural issue remains: policymakers can hold assets whose value is materially affected by decisions in the sectors they help govern.
And households paying higher diesel bills generally do not receive an equivalent hedge through ownership of a large energy portfolio.
Ownership question: Who has policy authority, who beneficially owns the assets affected by policy, who directs the transactions, what does the public filing establish, and what remains unproven?
14 · MARKET VOLATILITY
Every Lull in the Fighting Reprices the Same Physical Barrel.
There is another economic effect of this conflict that deserves its own section.
War does not have to end for enormous amounts of financial value to move.
The futures market continually prices expectations about future supply.
If traders believe a ceasefire will restore shipping, some of the geopolitical risk premium can disappear immediately.
The tanker may still be waiting offshore.
The refinery may still be damaged.
The insurer may still charge a war-risk premium.
But the financial market has already repriced the expectation.
Then another strike occurs.
The risk premium can return.
Oil moves.
Energy equities move.
Transport stocks respond differently.
Inflation expectations can change.
Bond markets may respond.
The same physical cargo can therefore be repriced several times before it reaches a refinery.
The difference between financial expectation and physical repair
A peace announcement does not rebuild a hydrocracker.
A negotiated shipping arrangement does not instantly refill a commercial diesel tank.
A pipeline restart does not automatically restore all damaged pumping capacity.
A lower Brent future does not guarantee a matching and immediate reduction in retail diesel.
These markets operate at different speeds.
That gap between price expectations and physical recovery is economically important.
September illustrates the distinction
Reuters reported that oil prices moved lower on expectations of possible U.S.–Iran diplomacy and improving Saudi export flows, while the physical shipping system remained impaired and reliant on costly alternatives. [11][17]
That does not make the price movement irrational.
It means traders were pricing a possible improvement in future conditions.
The physical system had not yet completed that improvement.
Information can be valuable before infrastructure changes
A company with reliable knowledge about future fuel deliveries can hedge differently.
A producer can lock in prices.
An airline can hedge jet fuel.
A refiner can alter purchasing decisions.
An investment manager can change portfolio exposure.
A public official may possess information about diplomatic or policy developments before those developments become public.
That last possibility is why the transaction-disclosure chronology matters.
But the existence of market volatility is not evidence that every person trading during the volatility possessed confidential information.
The correct research process is to document the trade, the public information available at the time, and any independently established information access.
The April 7 example is a sale, not a documented purchase of the lull
I want this point explicit because a false characterization would undermine the entire ownership analysis.
The large ExxonMobil transaction identified by CBS was a sale.
It does not prove Trump's accounts bought every pause in the fighting.
A broader recurring-pattern claim would require a complete date-by-date audit of purchases and sales across the relevant securities and conflict events.
What the record supports is that the President's accounts continued energy-security transactions during the conflict, including major diplomatic phases.
That is the documented starting point.
15 · INTERNATIONAL CAPITAL
The Capital Does Not Only Move Through Oil. It Moves Through the Financial System.
Now connect the physical energy market to the movement of capital.
There are several different channels, and they should not be treated as though they are one single flow.
Direct energy revenue
American producers, exporters, refiners and service companies may receive greater revenue when their products or capacity become more valuable.
Foreign direct investment
International investors may finance American LNG terminals, pipelines, energy infrastructure, manufacturing capacity, power generation and industrial projects.
Portfolio investment
Foreign investors may purchase American equities, corporate debt, Treasury securities and other dollar assets.
Commodity working capital
Higher commodity prices increase the nominal financing required to move the same physical volume.
A cargo worth $100 million requires more dollar financing than an otherwise identical cargo worth $70 million.
Longer shipping times can increase the duration for which financing remains committed.
Flight-to-liquidity demand
Periods of global stress can increase demand for highly liquid dollar assets and dollar funding.
That can occur even when the United States is directly involved in the geopolitical event.
What the Treasury data actually show
The U.S. Treasury's July 2026 International Capital data, released in September, reported approximately $83.7 billion in net TIC inflows.
That total consisted of approximately $73.5 billion in private inflows and $10.2 billion in official inflows. [25]
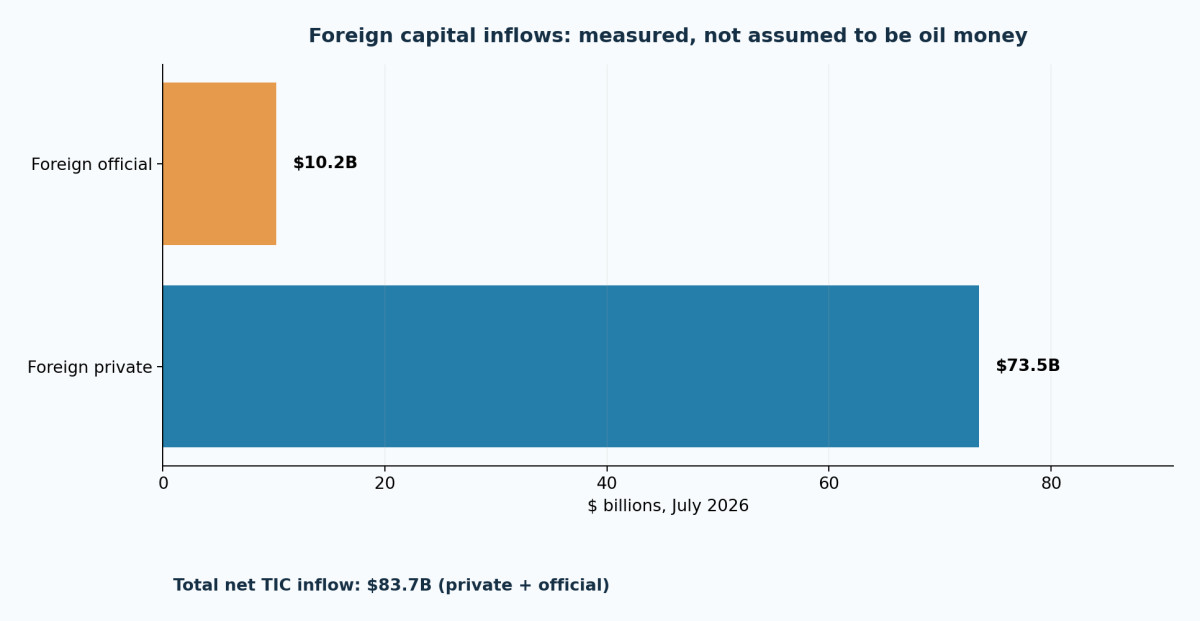
Figure 4. U.S. Treasury TIC, July 2026. Private and official net inflows sum to the reported total. This dataset does not identify the full amount attributable to petroleum or geopolitical capital redirection. [25]
That is evidence of substantial net capital entering U.S. financial assets during July.
It is not evidence that all $83.7 billion came from oil-producing countries or from the Iran conflict.
We need to distinguish what the data establish from the proposed mechanism.
How to test the energy-capital-redirection thesis
I would want to compare completed U.S. energy investment before and after the conflict.
Track new LNG agreements.
Track actual Venezuelan project financing.
Track purchases of American energy equities by foreign investors.
Track announced versus completed infrastructure spending.
Track sovereign-fund and institutional investment where public data permit.
Track Treasury and short-term dollar-asset purchases.
Track global dollar funding spreads.
Track changes in crude and refined-product trade flows.
Then compare the results against the pre-conflict baseline.
That would allow us to estimate the magnitude of any redirection rather than simply identifying a plausible channel.
The dollar can strengthen because the world is under pressure
Imagine an oil-importing country whose currency weakens as energy prices rise.
The country pays more dollars for the same fuel.
Each dollar also becomes more expensive in local currency.
The central bank may spend reserves to defend its exchange rate.
Domestic firms may require additional dollar credit.
Import financing becomes more expensive.
A global dollar shortage can therefore develop while energy prices remain high.
That is why I have repeatedly made this distinction:
A stronger dollar can be a signal of global stress rather than global economic strength.
Currency strength and real prosperity are not interchangeable.
16 · INFLATION AND THE DEBT
Can Oil Inflation Help Erase the National Debt? Yes, Mechanically. But There Is a Trap.
I have argued for years that heavily indebted monetary systems create structural incentives to tolerate some inflation rather than allow a prolonged collapse in nominal income and asset values.
That is an argument about debt mechanics and institutional incentives.
It is not independent proof that a particular war was organized for the purpose of inflating away government obligations.
Now let me explain the actual arithmetic.
How inflation erodes an existing nominal obligation
Suppose a government issued a fixed-rate bond promising to repay $1,000 at maturity.
As the general price level rises, the government still owes the same nominal $1,000.
But those dollars purchase fewer real goods and services.
The creditor receives the promised nominal amount.
The real purchasing-power value of the obligation has declined.
That is the basic debt-inflation mechanism.
If nominal GDP and nominal tax receipts also rise, the debt can become smaller relative to the nominal size of the economy.
But Treasury debt continuously refinances
The United States does not have a single permanent fixed-rate mortgage.
Treasury bills mature.
Notes mature.
Bonds mature.
New deficits require new borrowing.
As old debt matures, the government issues new securities at the yields investors require at that time.
Inflation can erode the real value of yesterday's fixed nominal liabilities while increasing the interest cost of tomorrow's financing.
That is the trap.
The debt arithmetic
A useful simplified debt-dynamics relationship is:
Change in debt/GDP ≈ (effective interest rate − nominal GDP growth) × existing debt/GDP + primary deficit/GDP.
That is an approximation. The precise accounting also depends on measurement conventions and other adjustments.
But it captures the underlying conflict.
If nominal GDP rises faster than the effective interest rate, the existing debt ratio can become easier to manage.
If refinancing costs rise faster, the interest burden becomes harder to manage.
If the government continues running substantial primary deficits, the debt ratio can continue increasing.
If real economic growth weakens while prices remain high, the situation can deteriorate on both the real-income and financing sides.
Why oil can push so many prices simultaneously
Oil affects gasoline.
Diesel affects freight.
Jet fuel affects aviation.
Marine fuel affects shipping.
Natural gas affects industrial power and fertilizer.
Petrochemicals affect manufacturing and packaging.
Energy therefore enters the economy through numerous production and distribution channels.
That is why a persistent petroleum disruption can contribute to inflation beyond the direct household energy category.
What actually happened to CPI
The Bureau of Labor Statistics reported August CPI rising 0.4% for the month and 3.4% over twelve months.
Gasoline rose approximately 3.9% in August. [26]
Those numbers help explain the monetary-policy problem.
If the public experiences higher gasoline and diesel prices while the inflation data move away from the central bank's target, policymakers face pressure to respond.
But monetary tightening does not directly rebuild a refinery or restore tanker access.
It can influence demand, expectations and financing conditions.
That may eventually reduce inflation.
It can also intensify cash-flow pressure in an economy already paying more for energy.
17 · THE FEDERAL RESERVE
The Fed Can Raise the Price of Money While Supporting the Plumbing Underneath It.
On September 16, the Federal Reserve raised its target range to 3.75%–4.00%. [7]
That is the decision I addressed in Fed Just Hiked Into a 5% 10-Year.
The important point was not simply that the Fed raised rates.
It was that the Fed had raised rates while the long end of the Treasury market was already near the stress levels I had been tracking.
In that article, I acknowledged that I had underestimated the Fed's willingness to tighten against the existing debt and refinancing burden.
The next question is what that combination does to the system.
The 10-year and 30-year are not ordinary market decorations
The Treasury curve provides the benchmark underneath large portions of private financing.
Mortgage rates are affected by Treasury and mortgage-backed-security yields.
Corporate borrowing begins with the benchmark risk-free curve and adds a credit spread.
Commercial-property financing reflects both the underlying rate environment and sector-specific risk.
Government interest expense is affected by refinancing at current yields.
A high long end therefore transmits restrictive financing conditions into the economy even when the central bank's policy-rate decision is only 25 basis points.
Nominal yields and real yields
There is another distinction that matters.
A high nominal Treasury yield can reflect expected inflation, real interest rates, term premium and other market forces.
High real yields increase the inflation-adjusted return investors require.
That can be especially restrictive for projects whose cash flows arrive many years in the future.
My earlier research examined this pressure on housing, commercial property, private credit and AI infrastructure.
The energy shock adds another demand for long-term capital while simultaneously raising the required cost of that capital.
The policy rate and reserve management are different instruments
The public still tends to think monetary policy has one lever.
Rates up: tightening.
Rates down: easing.
QE: printing.
No QE: no liquidity.
The modern operating system is more complicated.
The federal-funds target governs the intended marginal price of short-term money.
Reserve-management operations affect the supply of reserves.
Repo facilities affect secured funding.
Treasury issuance alters the supply and maturity distribution of collateral.
Treasury buybacks can improve liquidity in selected securities.
Long-duration asset purchases remove interest-rate risk from private portfolios.
Those are not identical operations.
The September Fed implementation note retains authority for Treasury-bill and, if necessary, other short-dated Treasury purchases to maintain ample reserves. [32]
That is not automatically a newly announced program to buy large quantities of ten- or thirty-year bonds.
Why duration matters
Buying a short Treasury bill changes reserve quantity while removing very little duration risk.
Buying a long Treasury bond removes significantly more duration risk from the market.
If the long end is the problem, a bill-focused reserve operation may not solve it.
That is why I separate liquidity support from duration support.
The Treasury market can become the transmission mechanism
Higher yields reduce the market value of existing fixed-coupon bonds.
Leveraged investors may face margin requirements.
Dealers may become less willing to warehouse additional securities.
Repo conditions can deteriorate.
Treasury auctions can clear at higher yields without formally failing.
The government can face higher interest costs at the same time that investors holding existing debt experience losses.
That is how a fiscal financing problem can interact with financial-market functioning.
The possible response ladder
Possible tools include standing repo facilities, ordinary reserve management, changes in Treasury issuance, Treasury buybacks and more direct support for market functioning.
In more severe circumstances, central banks can consider programs designed to absorb longer-duration securities.
Operation Twist-style maturity exchanges and explicit yield-curve control are different policy choices, not synonyms for reserve management.
I am not saying all those steps have been announced.
I am explaining the architecture available if financial conditions deteriorate.
Where LCPI and LCI-PCA fit
My liquidity work attempts to examine the system as a composite instead of treating one balance-sheet line item as the entire explanation.
Relevant variables include bank reserves, Treasury cash balances, money-market facilities, repo conditions, dollar funding, credit spreads, collateral availability and market depth.
A balance-sheet operation may support one part of the system without solving stress elsewhere.
The next liquidity phase, if it occurs, may first become visible in funding and collateral conditions rather than in a press release containing the words "quantitative easing."
18 · HISTORICAL POLICY ERROR
The Great Depression Comparison Is About Policy Transmission, Not an Identical Historical Replay.
I keep returning to the Great Depression because it is one of the clearest historical examples of a central bank making an existing financial and economic contraction worse.
But the comparison must be accurate.
The Federal Reserve tightened in 1928–29 partly in response to financial speculation.
It later raised rates in 1931 while defending the dollar's gold convertibility.
And it failed to provide sufficient monetary support during successive banking panics.
Those failures amplified the contraction. The Federal Reserve's own historical account explains the role of monetary policy, banking failures and gold-standard constraints in the severity of the Great Depression. [28]
Today's system is different. We have deposit insurance, a fiat currency, standing liquidity facilities and a different international monetary structure. But the underlying lesson survives: a central bank can intensify an economic contraction when it responds to the wrong part of a crisis or fails to recognize how stress is spreading through the financial system.
What makes the current setup different from an ordinary slowdown?
Consider what is happening simultaneously.
The physical economy is absorbing an energy shock. Households are paying more for fuel and transportation. Manufacturers and freight operators are facing higher costs. Countries dependent on imported energy are spending more foreign exchange to maintain consumption.
The Federal Reserve is responding to elevated inflation through restrictive interest-rate policy.
The Treasury market is simultaneously requiring higher compensation for longer-term lending. That affects refinancing across government debt, mortgages, corporate borrowing, commercial property and leveraged financial positions.
And the government must continue financing its obligations regardless of whether the private economy is growing comfortably.
Those are several different pressures operating on the same pool of income, savings, collateral and available capital.
The sequence I am concerned about
The initial shock increases prices.
The central bank responds by tightening financial conditions.
Higher financing costs weaken demand and reduce the ability of indebted businesses and households to absorb the original price increase.
Weaker demand begins affecting revenue.
Some borrowers become less able to refinance.
Credit spreads can widen.
Asset prices become more sensitive to financing conditions.
Collateral values become more important.
Investors who depend on leverage may have to reduce positions.
And then a problem that began with physical energy infrastructure can become a problem inside the financial system.
That is the connection I have been making between the Iran war, Treasury yields and the next liquidity cycle.
It is not a declaration that a depression is inevitable. It is an explanation of how the stress could propagate if several conditions deteriorate together.
The point where the response changes
A central bank can maintain restrictive interest rates while using separate facilities to preserve the functioning of funding markets.
That is not an imaginary contradiction. It follows from the fact that the price of short-term credit, the quantity of reserves, the availability of secured funding and the amount of duration held by private investors are different variables.
If inflation remains elevated but financial-market functioning deteriorates, policymakers may face competing objectives.
They may want to reduce demand without allowing disorderly failures in the financial infrastructure through which money and collateral circulate.
That is where reserve management, standing repo facilities, Treasury financing decisions and potentially other forms of market support become relevant.
I discussed that distinction in the September CPI report, in the September Fed-hike article and in QE 2026, Phase Two.
My concern is not that every rate hike automatically causes a recession.
My concern is that the policy rate can become an increasingly blunt instrument when the underlying inflation originates partly in physical constraints and the financial system is already heavily exposed to long-term refinancing costs.
The next significant break, if one occurs, may not begin with a conventional bank run. It could emerge through Treasury collateral, leveraged funding, private credit, energy-sensitive cash flows or the growing cost of maintaining the government's debt structure.
That is what I am watching.
19 · FOOD AND THE DELAYED SHOCK
The Food Problem Arrives After the Energy Headline.
I want to bring this back to agriculture because this is another part of the causal chain that does not receive enough attention.
In July, I published The Fertilizer Strait: Why the 2027 Food Shock May Already Be Forming.
The argument was not that the entire world was guaranteed to run out of food.
It was that disruptions to fuel, natural gas, fertilizer production, shipping and import financing can create agricultural consequences long after the original energy shock.
Natural gas becomes fertilizer
Natural gas is an important feedstock and energy source for ammonia production.
Ammonia is used to manufacture nitrogen fertilizers.
Nitrogen fertilizers are essential to a large portion of modern agricultural production.
That creates a physical relationship between natural-gas availability and future crop-input costs.
If gas becomes expensive or unavailable, fertilizer production can become less economical.
If fertilizer becomes more expensive, farmers may alter application rates, planting decisions or purchasing schedules.
If those decisions affect crop yields, the consequences can appear during a later harvest rather than immediately after the original gas disruption.
Diesel adds another layer
Farm equipment needs fuel.
Grain must be transported.
Fertilizer must be delivered.
Food must be processed, refrigerated and distributed.
Diesel therefore enters the agricultural system repeatedly, from the field to the consumer.
Now combine that with the simultaneous pressure on Russian and Gulf refined-product supply.
A shortage in the diesel market can affect agricultural operating costs even where the local natural-gas or fertilizer supply remains relatively stable.
Not every country experiences the same shock
A large grain exporter with reliable domestic energy and a strong currency has a very different exposure from an importing country with limited foreign-exchange reserves.
A country dependent on imported fertilizer may face higher agricultural costs before planting.
A country dependent on imported food may face higher prices after harvest.
A country whose currency is depreciating may face both increases simultaneously.
That is the double-price problem I have repeatedly described.
The commodity becomes more expensive in dollars.
The dollar becomes more expensive in local currency.
The same physical shipment becomes significantly harder to purchase.
The World Food Programme's warning
In its April 2026 analysis, the World Food Programme modeled the potential impact of the Middle East conflict on acute food insecurity.
The agency estimated that prolonged energy-price increases and the resulting domestic price pressures could push approximately 45 million additional people into acute hunger across the 53 countries included in its analysis, compared with its modeled pre-conflict baseline of 318 million. [42]
That was a conditional scenario based on the duration and economic consequences of the conflict.
It was not a statement that 45 million people had already entered famine.
Acute food insecurity and famine are not interchangeable terms.
Famine is a much more severe condition involving extreme food-consumption gaps, malnutrition and elevated mortality.
The 2027 question
The reason I raised 2027 in the fertilizer article was timing.
An energy shock can affect fertilizer production today.
Fertilizer prices can affect planting decisions in the next agricultural window.
Those decisions can affect harvest volumes later.
Higher transportation and processing costs can persist after crude futures begin falling.
And households may experience food-price pressure after the original war headline has already moved on.
That is why the agricultural risk must be monitored through input prices, fertilizer availability, planted acreage, application rates, weather, crop yields, grain inventories and import financing rather than through oil prices alone.
The energy shock becomes a food problem when the cost or availability of fuel and fertilizer begins affecting production, distribution or the ability of households to purchase the food that still exists.
That is a much more useful framework than declaring a worldwide famine because oil increased in price.
20 · IRAN AND THE ESCALATION LADDER
Iran Can Experience a Prolonged Infrastructure War Without a Full American Occupation.
Now we have to return to Iran itself.
I have considered several possible military paths throughout this conflict, including the possibility that pressure around Hormuz eventually moves toward limited coastal operations.
That was the framework behind The Hormuz Theory in March.
The important distinction was always between securing commercial shipping, conducting limited operations against threats to shipping, holding territory and attempting to occupy an entire country.
Those are very different military undertakings.
Iran is not a small occupation problem
Iran has substantial territory, difficult terrain, large urban areas, established military and paramilitary institutions, and numerous means of imposing costs on a foreign force.
Modern military technology does not eliminate the logistical and political requirements of holding territory.
An air campaign can damage a military facility without controlling the population or the surrounding geography.
A limited coastal operation can suppress or contain a particular threat without establishing durable national control.
A full occupation requires prolonged security, administration, supply, reconstruction and political arrangements.
It also commits forces and equipment that cannot simultaneously be used elsewhere.
The historically accurate point is not that Persia has never been invaded. It has experienced numerous invasions.
The point is that military entry, defeating an organized force and establishing durable political control are different problems.
What has changed in my scenario analysis?
I do not treat a large American occupation as the automatic next stage of the conflict.
The military, fiscal, logistical and domestic political requirements are substantial.
The alternative is not necessarily peace.
A conflict can continue through air operations, maritime confrontation, drone attacks, sanctions, covert activity, limited territorial operations and repeated strikes against military infrastructure.
Those forms of pressure can persist without a permanent occupation.
That is why I have been watching the transition from an immediate military campaign into a longer contest over the systems that allow Iran to sustain its military and commercial activity.
The Libya comparison
I previously used Libya as a comparison for what can happen when a military campaign damages a state's capacity without producing a stable replacement political order.
The comparison should not be taken literally.
Iran and Libya differ substantially in population, geography, state institutions, economic organization and regional relationships.
The relevant historical issue is the distinction between weakening a government militarily and establishing the conditions for long-term economic and political stability afterward.
Infrastructure destruction can make reconstruction substantially more difficult.
It can also produce political fragmentation rather than a predictable transition.
That is the concern I am examining when I discuss a prolonged infrastructure-war scenario.
Infrastructure warfare has an economic half-life
Consider the difference between destroying a military vehicle and damaging a major electricity substation.
The vehicle is a direct military asset.
The substation may supply military users, but it may also support hospitals, drinking-water pumps, residential neighborhoods, telecommunications and civilian industry.
Damage to the substation can affect those systems long after the immediate strike.
The same applies to bridges, rail corridors, ports, water facilities and other infrastructure.
A bridge can serve military logistics and civilian food distribution.
A power plant can support military communications and civilian hospitals.
A water system can become a major public-health issue when electricity and treatment capacity fail.
Those are not incidental details.
They determine the human and economic consequences of a prolonged campaign.
The legal and humanitarian distinction
Civilian infrastructure is not automatically a lawful military target because destroying it would increase pressure on a government.
International humanitarian law requires parties to distinguish military objectives from civilian objects, assess proportionality and take feasible precautions.
Whether particular dual-use infrastructure constitutes a military objective depends on the circumstances.
The United Nations warned in April that damage to civilian infrastructure across the Middle East, including bridges, water facilities and power plants, was undermining essential services and imposing severe consequences on civilians. [43]
On September 17, Reuters reported that a UN fact-finding mission had found reasonable grounds to believe U.S. strikes on civilian sites in Iran constituted war crimes. The mission also reported crimes against humanity by Iranian authorities in their repression of protests. The U.S. administration rejected the mission's findings. [44]
These findings are distinct from the market and military scenarios developed in this article.
They matter because the consequences of an infrastructure campaign must include the people living inside the affected system.
Now connect the military cost to the economic cost
This is where The Lincoln Trap becomes relevant.
Aircraft require maintenance.
Ships require maintenance.
Interceptors are finite.
Precision weapons have manufacturing lead times.
Crews cannot remain deployed indefinitely without consequences.
Military operations consume readiness and industrial capacity as well as money.
A missile used in the Gulf is no longer in the inventory available for another contingency.
A carrier committed to one theater changes the readiness available elsewhere.
That is the military version of the oil inventory clock.
The November election is a political checkpoint, not proof of a secret schedule
I have discussed the possibility that the election calendar affects the timing and political presentation of military decisions.
Fuel prices and the costs of war are visible domestic issues. Officials have to account for them when deciding how to explain and conduct policy.
But the existence of an election does not prove that the parties have agreed to escalate into a larger war afterward.
Congressional support for some sanctions does not automatically establish support for a particular military campaign.
And the public record does not establish a confirmed post-election operation.
What I can do is identify the military and political constraints, describe the possible forms of escalation, and watch for observable changes in deployments, authorizations, force posture, diplomacy and logistics.
That is more useful than turning a contingent scenario into an announcement before it happens.
The larger economic point
A prolonged campaign can keep the energy and shipping system impaired even without a large occupation.
Repeated military activity can sustain insurance costs, tanker delays, infrastructure-repair needs, fuel scarcity and uncertainty around commercial investment.
Those conditions can continue affecting the global economy after the initial military objectives have changed.
Which means the financial consequences of the war may outlast particular battlefield phases.
That is why I do not view the Iran conflict only through the next military operation.
I view it through the duration of the damage imposed on the surrounding economic system.
21 · THE COMPLETE SYSTEM
Here Is the Entire Pattern Nexus Causal Chain I Am Watching.
I want to put all the pieces together now.
Throughout the year, each article examined a different portion of this machinery. The Venezuela research examined resource access and strategic control. The Iran articles examined military escalation and chokepoints. The inventory research examined time. The fertilizer article examined the delayed agricultural consequences. The petrodollar article examined the changing American position. The Fed and QE work examined monetary transmission.
Those were not isolated subjects for me.
They were components of the same framework.
Stage 1 — Physical energy infrastructure becomes less reliable
Ukraine damages Russian refining capacity.
The Gulf conflict restricts production, refining, shipping or export access.
The Strait of Hormuz becomes commercially impaired.
Saudi Arabia's alternative pipeline experiences damage.
Red Sea insecurity complicates alternative shipping.
LNG facilities face damage and delayed investment.
The system loses reliability across several different stages at once.
Stage 2 — The conversion and delivery systems become more valuable
Crude remains available in some locations, but the ability to convert and deliver the appropriate petroleum product becomes relatively scarce.
Operational refineries can receive wider margins.
Available tanker capacity becomes more valuable.
Alternative pipelines and ports become more important.
Shipping insurance and financing become larger components of the delivered cost.
Stage 3 — Inventories absorb the first shock
Commercial stocks are drawn down.
Strategic petroleum reserves are released.
Floating storage and ship-to-ship transfers expand.
Countries with larger inventories buy time.
Countries with limited reserves depend more heavily on immediate imports and current market prices.
Stage 4 — The scarcity value of alternative energy systems changes
Reliable American production becomes more commercially valuable under some market conditions.
American refining can become more important.
North American LNG can attract additional interest.
Venezuelan resource development offers a long-term Western Hemisphere supply option.
Oil-field services, electricity infrastructure and project financing receive new opportunities.
That is the resource-realignment component.
Stage 5 — Ownership determines the distribution of gains
Producers may receive higher prices.
Refiners may receive stronger product margins.
Some infrastructure companies may receive new contracts.
Shareholders may receive higher earnings or valuations.
Traders may profit from volatility or physical market dislocations.
Public officials may have financial exposure to companies affected by policy.
At the same time, fuel-intensive businesses and households absorb increased costs.
That is the ownership and distribution component.
Stage 6 — Capital adjusts geographically
Investment may move toward alternative energy infrastructure.
Foreign buyers adjust supply contracts.
Energy companies change capital-expenditure plans.
Importing countries alter reserve usage and financing.
Financial investors reconsider the relative value of dollar assets, commodities and industrial capacity.
Actual movement must be tested against capital-flow data rather than inferred from a single headline.
Stage 7 — Energy costs spread into general prices
Fuel costs enter transportation.
Transportation enters goods prices.
Natural gas enters fertilizer.
Fertilizer enters agriculture.
Industrial energy enters manufacturing.
Higher operating costs and constrained supply contribute to inflationary pressure.
Stage 8 — The real economy begins adjusting
Households reduce discretionary consumption.
Businesses postpone investment.
Freight volumes may weaken.
Import-dependent countries conserve currency reserves.
Demand destruction begins reducing the quantity of energy the economy can afford to consume.
Stage 9 — Inflation and Treasury financing collide
Inflation can reduce the real value of existing fixed-rate nominal debt.
Investors may demand higher yields to finance new debt.
Government refinancing becomes more expensive.
Mortgage and corporate borrowing costs rise.
Higher yields reduce the market value of existing fixed-coupon securities.
The debt structure becomes more sensitive to the duration of the shock.
Stage 10 — Restrictive monetary policy interacts with weaker cash flow
The Federal Reserve attempts to contain inflation.
The policy rate influences demand and financing.
Physical refinery or shipping disruptions may persist.
Borrowers face higher interest costs and higher operating costs simultaneously.
Some balance sheets become less resilient.
Stage 11 — Financial stress becomes possible
Credit spreads may widen.
Borrowers may have greater difficulty refinancing.
Collateral values can become more volatile.
Leveraged Treasury positions may require adjustment.
Repo markets can become more sensitive to cash and collateral conditions.
Dealer balance sheets may become less willing to absorb additional securities.
Stage 12 — The policy response may change
If markets remain orderly and inflation recedes, the more severe financial-stress scenario may not materialize.
If funding or collateral conditions deteriorate, policymakers may use targeted liquidity tools.
Reserve management, repo facilities, Treasury financing decisions and market-functioning support can change without an immediate reversal of the inflation-policy stance.
More direct duration intervention would be a separate and more consequential policy development requiring evidence of adoption.
Stage 13 — The next cycle begins from the resulting nominal and financial structure
If the economy stabilizes through repairs, restored trade and lower inflation, the system can move into a different adjustment path.
If stabilization instead relies heavily on additional financial intervention while debt, asset prices and nominal obligations have grown, the next cycle may begin from a larger and more complicated balance-sheet structure.
That is the feedback loop I have been examining throughout my liquidity work.
Complete Pattern Nexus chain: geopolitical disruption → energy conversion and delivery constraints → inventory depletion and higher logistics costs → changing ownership and capital flows → inflation and weaker purchasing power → Treasury and refinancing pressure → possible credit and funding stress → potential liquidity intervention.
The final steps are conditional.
One disruption does not automatically produce every subsequent event.
But identifying the links gives us a way to monitor whether the system is moving toward stabilization or transmitting stress into another layer.
That is the value of the framework.
22 · THE EVIDENCE CHECKPOINTS
What Would Change This Analysis?
A causal framework is not useful if every possible outcome is treated as confirmation.
So I want the conditions that would weaken or change the argument stated clearly.
The physical shortage thesis weakens if the network recovers
Sustained recovery in Hormuz transit, normalizing freight and insurance costs, restored Saudi pipeline capacity, improving Russian refinery utilization and replenishing commercial petroleum inventories would all reduce evidence of a persistent physical shortage.
A reduction in SPR dependence would also be relevant.
One successful tanker transit or one temporarily restarted refinery would not establish that the entire system had normalized.
I would want sustained operating data.
The Venezuela buildout thesis requires completed investment
Signed agreements are evidence of commercial intent and legal structure.
They are not evidence that the forecast production has already arrived.
Actual capital expenditure, completed electricity infrastructure, additional operational wells, improved production and higher exports would strengthen the new-supply thesis.
Legal challenges, investment delays, unfavorable project economics or deteriorating operating conditions could weaken it.
The ownership analysis needs complete transaction records
Public disclosures establish financial exposure and reported transactions.
They do not automatically establish motive or material nonpublic information.
A more extensive audit should include purchases and sales, exact reported trade dates, disclosure dates, beneficial ownership, the degree of independent management and relevant policy authority.
If those records reveal no unusual trading pattern after controlling for broad portfolio activity, that would matter.
If stronger evidence establishes a connection between undisclosed information and particular transactions, that would also matter.
The data have to decide.
The capital-redirection argument needs actual flow measurement
Announcements of investment and observed foreign capital inflows are useful.
They do not prove the origin or motivation of every dollar.
Completed projects, identifiable foreign investment, actual energy purchases, securities flows and comparison with the pre-conflict baseline are necessary to quantify the mechanism.
The inflation-to-liquidity scenario weakens if adjustment remains orderly
Lower energy inflation, stable real growth, contained credit spreads, orderly Treasury auctions, sufficient reserves and normal repo functioning would weaken the more severe financial-stress scenario.
Persistently high long-term yields combined with weak refinancing, wider spreads, collateral pressures and impaired market depth would warrant closer examination.
The distinction is between observing vulnerability and declaring an unavoidable break.
China could change several branches of the chain
The Trump–Xi meeting may clarify parts of the commercial relationship between the two countries.
The meaningful evidence will be subsequent actions: energy contracts, cargo flows, tariff implementation, sanctions licenses, rare-earth access, financial commitments and changes in the treatment of Iranian or Russian petroleum.
A press conference may move markets immediately.
A durable change in the physical economy requires changes in actual operating conditions.
The unresolved part of my original framework remains unresolved
I have not established enough evidence to publish that later scenario as a predetermined event.
It is still part of the broader set of developments I am monitoring.
But the published record should distinguish the things I identified early, the things that changed, the things that happened differently than expected and the things that have not happened at all.
That is how the reader can judge the work without needing to accept every interpretation I make.
23 · FINAL THOUGHT
The Same Machine Can Make One Balance Sheet Stronger While Breaking Another.
This is what I have been trying to explain throughout the entire research chain.
People keep looking for one universal outcome.
Was the Iran war economically beneficial or damaging?
Are higher oil prices beneficial or damaging?
Does a stronger dollar help or hurt?
Does inflation reduce the debt or increase it?
Does Venezuela's energy recovery increase American influence or reduce international oil prices?
Those questions do not have one uniform answer because the effects fall on different people, companies, countries and financial obligations.
A higher oil price can increase a producer's revenue while reducing a consumer's purchasing power.
A diesel shortage can increase the value of an operational refinery while damaging a trucking company.
A stronger dollar can increase the pressure on a foreign borrower carrying dollar-denominated liabilities.
Inflation can reduce the real burden of an old fixed-rate Treasury obligation while making new borrowing more expensive.
A public petroleum-reserve release can support today's consumption while reducing the inventory available for the next emergency.
A ceasefire can move billions of dollars in financial-market value before a single refinery has been repaired.
A government official can make a policy decision while retaining beneficial ownership of securities affected by that policy, creating a financial-exposure question that requires documentation rather than assumption.
A country can lose productive capacity while international investors find opportunities in rebuilding it.
These are not contradictions.
They are different balance sheets inside the same operating system.
And that is the part I want you to see.
The Iran war is not economically isolated from the Ukraine war.
Russian refining is not isolated from Gulf diesel exports.
Hormuz is not isolated from Saudi Arabia's alternative pipelines or the Red Sea.
Venezuela is not isolated from American refinery configuration or long-term infrastructure investment.
Cuba is not isolated from fuel access and the financing of civilian infrastructure.
China is not isolated from the dollar, American LNG, Iranian crude or Russian energy.
The Federal Reserve is not isolated from the price of diesel, Treasury financing or the operating cash flow of the real economy.
And the people who own the assets are not isolated from the policies and market conditions affecting those assets.
I am not saying every part was centrally planned.
I am saying the parts affect one another whether anyone planned them to or not.
Watch the barrels.
Watch the refineries.
Watch the pipelines.
Watch the tankers.
Watch the inventories.
Watch who owns the assets.
Watch where the capital moves.
Watch the 10-year and the 30-year.
Watch the repo market.
And watch what actually happens after Trump and Xi meet this week.
That is where I am looking for the next observable part of the chain.
PATTERN NEXUS · THE CONNECTED RESEARCH RECORD
Previous Pattern Nexus Research: Read the Entire Chain in Order
This is the research history behind the article. I want readers to be able to follow the development of the framework rather than encounter only my September interpretation.
The earlier pieces establish what I was watching before the war, how the analysis changed after the February escalation, where the physical and financial arguments developed, and which calls remained incomplete or moved differently than expected.
The longer reports and the shorter AI Nexus dispatches serve different purposes. The longer pieces establish the framework. The dispatches document individual developments as the situation changes.
Where a direct original-language article URL is confirmed, it is linked directly below. Where the older report's exact destination is not established in this research record, the link opens the corresponding Pattern Nexus search rather than an invented article address.
JANUARY — THE WARNING STRUCTURE
-
January 2 — The Middle East Fragmentation Regime. This report examined overlapping regional conflicts involving Iran, Israel, Yemen, the Red Sea and Gulf relationships. Its contribution to the present article is the idea that apparently separate regional confrontations can affect the same shipping and energy architecture.
-
January 3 — Iran at the Edge: Currency Collapse, Protests and Red Lines. The internal Iranian economy and the external military environment were examined together. Currency instability, protests and government pressure were treated as conditions affecting the broader escalation environment rather than a prediction of an inevitable immediate collapse.
-
January 12 — The Iran Decision Window. Reported military, cyber and psychological options were compared with the observable decision environment. The report distinguished available options from confirmed orders.
-
January 14 — Iran's Decision Window: Blackouts, Embassy Pullbacks and Airspace. Diplomatic withdrawals, information restrictions, regional airspace, protective measures and retaliation indicators were combined into a framework for tracking escalation without claiming access to private operational plans.
FEBRUARY AND MARCH — THE CHOKEPOINT WAR BECOMES VISIBLE
-
February 28–March 5 — Iran and the Middle East War, Day by Day. The opening strikes, retaliation and regional escalation were reconstructed chronologically. The research moved from assessing potential military action to examining the effects of a conflict already underway.
-
March 1 — Hormuz, Tankers and Regional Energy Disruption. This research connected the developing military conflict to tanker movement, commercial shipping and the economic consequences of uncertainty around Gulf energy exports.
-
March 2 — Oil, Gold, Volatility and the Immediate Market Response. The first market reactions were compared with the longer physical supply risk. An immediate financial price movement was not treated as a complete measure of the eventual economic damage.
-
March 5–22 — Iran War, Energy Prices and the Treasury Market. These updates examined how oil, gold, the dollar and Treasury yields were responding to changing military and commercial conditions. They established the link between the energy conflict and the broader liquidity framework.
-
March 25 — Middle East Force Posture Update: 82nd Airborne, Marine Lift and the Iraq Drawdown. This article distinguished troops preparing to deploy, units already moving, forces in theater and advisory forces leaving exposed positions. It was part of the effort to keep operational readiness separate from a confirmed decision to initiate a particular campaign.
-
March 26 — The Hormuz Theory: Could a Coastal Safe Zone Become the Front Edge of a Long War in Iran? This was the conditional coastal-pressure framework. It examined how a maritime protection mission might expand if the threat to shipping persisted, while distinguishing a limited territorial operation from a full occupation.
-
March 28 — Liquidity Needs a Cover: War, Control Systems and the Next Monetary Response. This article connected the political acceptability of financial intervention to a highly visible external shock. Its thesis concerned how a crisis can alter the operating environment for policy, not proof that the crisis was deliberately manufactured for monetary purposes.
-
March 29 — The Clock Starts at Hormuz: Oil Corridors and Timed Failure. This report established the inventory-clock argument. It examined how countries and industries experience a shipping disruption at different times depending on stored supply, product availability, logistics and purchasing power.
-
March 31 — March Ends With the System Showing Its Seams. The month-end synthesis connected Hormuz, insurance, oil prices, inflation, household costs, liquidity, infrastructure and industrial constraints. The central theme was that physical and financial systems were revealing their interdependence.
APRIL AND MAY — THE CONFLICT BECOMES A LONGER SYSTEMS PROBLEM
-
April 11 — Why I've Been Quiet. This personal research update explained why the growing number of simultaneous geopolitical, monetary, market and infrastructure developments required more careful analysis instead of reacting to individual headlines.
-
May 1 — The UAE, Dollar Funding, Swap Lines and Treasury Architecture. The Gulf relationship was examined through dollar financing, liquidity arrangements and the securities markets that support international trade. This is part of the monetary layer behind the current energy article.
-
May 7 — The Headline Is Late: How Pattern Nexus Mapped the Chokepoint War Before Hormuz Became Visible. This retrospective connected the developing conflict to the earlier PN work on Western Hemisphere positioning, energy corridors, China, liquidity, Treasury collateral, sanctions and the changing physical requirements of global industry.
-
May 14 — The War Economy and Industrial Capacity. The focus widened to munitions, manufacturing, supply chains and the difference between possessing financial purchasing power and possessing the physical industrial capacity to replace equipment quickly.
JUNE — INVENTORIES, GOLD AND THE LONG-END PROBLEM
-
June 1 — The Oil Cushion Is Breaking. This developed the original Hormuz inventory-clock thesis through commercial stocks, strategic reserves, refining limitations, shipping and the potential movement from an energy shock into financial stress.
-
June — Gold and the 10-Year Treasury: The Forecast Retrospective. The public record examined the difference between the gold thesis and the interest-rate path. The earlier expectation for the 10-year Treasury did not unfold as originally anticipated, and the effect of war and term premium became important to the revised analysis.
-
June 19 — The Peak Insanity Scenario. This was explicitly speculative scenario research linking several geopolitical and market pressures. Its importance here is the distinction between mapping potential interactions and treating every scenario as a confirmed future event.
JULY — THE PHYSICAL, GEOPOLITICAL AND MONETARY SYSTEMS CONVERGE
-
July 9 — Iran War: Rail, Bridges and Network Isolation. The discussion moved beyond southern maritime access to northern trade and transport routes. The article examined the wider system linking Iran to Central Asia, Russia and China, while distinguishing damage to an individual bridge from the permanent severing of an entire continental network.
-
July 18 — The Petrodollar Did Not Die. It Mutated Into the Commodity Dollar. This is a foundational piece for the present article. It examined how U.S. energy production, exports, refining, financial-market depth, sanctions and maritime relationships changed America's position inside the global commodity system.
-
July 24 — The System Repriced in 30 Days. The research connected dual maritime chokepoints, changing trade relationships, energy, tariffs, AI capital expenditure and the tightening constraints on global economic activity.
-
July 24 — The Fertilizer Strait: Why the 2027 Food Shock May Already Be Forming. This examined how natural gas, nitrogen fertilizer, diesel, maritime disruption and agricultural purchasing windows could transmit the war into later food-production and food-access problems.
-
July 24 — The Red Sea and the Second Chokepoint. The second maritime route was linked to the Hormuz problem. The article examined why sending crude or products through an alternative route does not eliminate freight, insurance, vessel-capacity or security constraints.
AUGUST — THE INVENTORY, MILITARY AND FORECAST AUDITS
-
August 2 — The Oil Inventory War Machine: How Long the Global Buffer Can Hold. The long-form inventory reconstruction connected historical stocks, the U.S. Strategic Petroleum Reserve, physical supply constraints, price behavior, inflation, recession and liquidity scenarios.
-
August 14 — The Lincoln Trap: 265+ Days Deployed, an Indefinite Iran War and a Carrier Gap in the Pacific. This examined the military inventory clock: readiness, ships, aircraft, maintenance, munitions and the opportunity cost of a prolonged deployment across multiple theaters.
-
August 18 — The Price of a Fractured World: Why the 30-Year Treasury Is Sending a Geopolitical Signal. The research examined how geopolitical instability, inflation expectations and term premium can influence long-duration Treasury financing and the wider cost of capital.
-
August 20 — From Liquidity Storm to Chokepoint War: Auditing 472 Pattern Nexus URLs. This public-record audit reconstructed the earlier calls, including Venezuela, Iran, Hormuz, liquidity and the 10-year Treasury. It distinguished developments consistent with the framework from calls whose timing or price path did not materialize as expected.
-
August 22 — One System, Many Flags: Ukraine, Iran, North Korea and the Illusion of Separate Wars. This connected weapons supply, sanctions, energy, intelligence, logistics and military readiness across multiple conflicts. It is particularly relevant to understanding why the Ukraine and Iran wars can affect the same material and financial resources.
SEPTEMBER — THE CURRENT ENERGY-INFLATION AND FED FRAMEWORK
-
September 11 — August CPI and the Fed-Hike Trigger. This report examined the August inflation data, energy-price transmission, the Fed's September decision and the interaction between the policy rate and the long-end Treasury market.
-
September 11 — QE 2026, Phase Two: When the Long End Forces Duration Control. This expanded the monetary framework into reserve management, Treasury issuance, buybacks, collateral, repo, real yields, duration exposure and possible market-functioning interventions.
-
September 17 — Fed Just Hiked Into a 5% 10-Year: Why the Next Liquidity Cycle May Arrive Faster. This examined the actual September rate increase, the restrictive long end and the possible interaction between monetary tightening and funding-market support.
Short AI Nexus updates and the live archive
Several shorter dispatches followed sanctions announcements, Gulf shipping, Russian energy waivers, Chinese oil purchases and individual military developments. These are useful as dated checkpoints alongside the larger research articles.
Open the live Pattern Nexus Iran research and AI Nexus dispatch archive →
FREQUENTLY ASKED QUESTIONS
Frequently Asked Questions
Is this article claiming that the United States deliberately created every disruption to benefit its economy?
No. The article examines observable interactions among geopolitical conflict, physical energy infrastructure, financial ownership and monetary conditions. Some American industries can benefit from changes in relative supply or investment opportunities. That does not independently establish that the events were coordinated or that a particular official initiated a conflict for that financial purpose.
Why can the United States benefit from high oil prices while Americans pay more for gasoline and groceries?
Because producers, refiners, shareholders and consumers have different economic exposures. A higher price may increase revenue for a producer while increasing costs for a trucking company or household. The result is a redistribution of income and purchasing power rather than a uniform gain or loss for every American.
Why does Russia's refining capacity matter to the Iran war?
Russia and Gulf exporters supply parts of the same international refined-product market. Damage to Russian refining and disruption to Gulf diesel exports can reduce the availability of replacement cargoes at the same time. The wars have different causes and objectives but can interact through global petroleum balances.
Why is diesel more important than looking only at Brent crude?
Diesel is a finished petroleum product used throughout freight, agriculture, construction, mining and industry. Its availability depends on refinery output as well as crude supply. Diesel prices can remain elevated even if crude prices fall because the conversion and delivery bottlenecks have not been repaired.
Does the Venezuela agreement mean 65 billion barrels of oil are immediately available to the United States?
No. Reserves underground, production capacity, actual output and export availability are different measures. Developing Venezuelan resources requires infrastructure, electricity, financing, equipment, labor and durable commercial arrangements.
Is Cuba under a complete physical naval blockade?
The article uses energy blockade to describe the economic effect of restrictions that severely constrain fuel access. It does not establish that every Cuban port is physically sealed by a continuous naval cordon. Cuba's grid crisis also reflects domestic infrastructure and economic problems.
Did Trump personally order the reported ExxonMobil sale before the April 7 ceasefire announcement?
The reported financial disclosures establish a sale by his investment accounts and the chronology relative to the announcement. They do not independently establish who instructed the transaction or whether advance knowledge was used. The White House says independent discretionary managers direct the accounts' individual trades.
Does the public record show that officials bought energy stocks during every lull in the fighting?
The available reporting establishes energy-security purchases and sales during major phases of the conflict. It does not establish a complete recurring pattern of purchases during every pause. That stronger claim would require a comprehensive transaction-level audit.
How can inflation reduce the real value of the national debt while increasing federal interest expense?
Inflation erodes the real purchasing-power value of existing fixed nominal obligations. But the Treasury continuously refinances maturing debt and finances new deficits. Higher market yields can increase the cost of new borrowing, offsetting some or all of the benefit from inflation.
Does an expanding Fed balance sheet automatically mean quantitative easing has restarted?
No. Reserve-management purchases, temporary funding operations and long-duration asset purchases can have different objectives and market effects. Increasing bank reserves is not identical to purchasing substantial quantities of long-term Treasury securities to reduce duration exposure in private portfolios.
Is Pattern Nexus predicting an inevitable depression or another round of QE?
No. The article identifies a conditional transmission mechanism from physical energy disruption to inflation, refinancing pressure and possible financial-market stress. Restored energy flows, lower inflation, stable credit conditions and orderly funding markets could weaken the more severe scenario.
What should readers watch after the Trump–Xi meeting?
Actual changes in energy purchases, sanctions implementation, commercial licenses, tariff arrangements, LNG contracts, physical cargo flows and financing conditions. Those developments will reveal more about the economic consequences than diplomatic language alone.
RESEARCH RECORD
Sources and Research Notes
The article distinguishes official releases, reported developments, disclosed financial transactions, estimates, forecasts and Pattern Nexus interpretations. Financial-disclosure ranges are not exact amounts or audited gains. A reported policy or investment agreement is not equivalent to completed implementation. Research and market forecasts are not established outcomes.
- International Energy Agency — September 2026 Oil Market Report, September 11, 2026.
- Reuters — Russian diesel-producing refineries reduce output following Ukrainian strikes, September 15, 2026.
- Reuters — Three Saudi East–West pipeline pumping stations damaged, September 17, 2026.
- Associated Press — Cuba experiences another nationwide blackout, September 2026.
- White House — U.S.–Venezuela oil agreement fact sheet, August 31, 2026.
- U.S. Energy Information Administration — American crude-oil production and international producer comparison.
- Federal Reserve — September 16, 2026 FOMC statement.
- Reuters — Russian diesel deliveries to Central Asia under export exemptions, September 21, 2026.
- United Nations Human Rights Monitoring Mission in Ukraine — Attacks on Ukrainian energy infrastructure, June 2026.
- Financial Times — Reported U.S. pressure concerning Ukrainian refinery strikes, September 21, 2026.
- Reuters — Hormuz ship-to-ship transfer operations and freight costs, September 21, 2026.
- U.S. Energy Information Administration — Weekly U.S. ending stocks of crude oil in the Strategic Petroleum Reserve.
- U.S. Department of Energy — Venezuela energy agreements involving Chevron, Eni and GE Vernova, September 2, 2026.
- Reuters — Halliburton Venezuelan energy memorandums, September 21, 2026.
- Federal Register — U.S. executive action and Cuba sanctions, May 2026.
- Chinese Foreign Ministry — Xi Jinping's scheduled U.S. visit, September 21, 2026 announcement.
- Reuters — Oil-market reaction to regional attacks and possible U.S.–Iran diplomacy, September 2026.
- CBS News — Trump's reported oil-and-gas stock transactions during the Iran conflict, August 2026.
- Joint Economic Committee Democratic staff — Analysis of Trump's disclosed energy holdings, August 2026.
- Quiver Quantitative — Congressional Chevron transaction ledger.
- Quiver Quantitative — Congressional EOG Resources transaction ledger.
- Congressional Trader — Chevron transaction records and disclosure references.
- U.S. Senate Ethics Committee — Financial disclosure and periodic transaction reporting requirements.
- MarketWatch — Energy-company insider purchases during the Iran conflict, September 21, 2026.
- U.S. Treasury — Treasury International Capital data for July 2026, released September 2026.
- Bureau of Labor Statistics — August 2026 Consumer Price Index report.
- Reuters — U.S. 10-year Treasury yield reaches approximately 5%, September 14, 2026.
- Federal Reserve History — The Great Depression and Federal Reserve policy.
- Pattern Nexus — Live Iran research archive.
- Pattern Nexus — The Petrodollar Did Not Die. It Mutated Into the Commodity Dollar.
- Pattern Nexus — The Deficit Never Ends: Federal Debt and the Long-Term Baseline.
- Federal Reserve — September 16, 2026 Implementation Note.
- Pattern Nexus — The Fertilizer Strait: Why the 2027 Food Shock May Already Be Forming.
- Financial Times — Congressional action concerning Russian oil and Iran sanctions, September 2026.
- Pattern Nexus — The Lincoln Trap.
- Quiver Quantitative — Congressional Occidental Petroleum transaction ledger.
- Reuters — Structure of the U.S.–Venezuela petroleum arrangement, August 31, 2026.
- Reuters — Legal and transparency questions concerning the Venezuela oil agreement, August 31, 2026.
- Reuters — QatarEnergy and possible LNG expansion delays, September 21, 2026.
- Reuters — LNG buyers and sellers seek greater supply diversity amid the Iran war, September 21, 2026.
- Reuters — Vessel traffic through Hormuz amid continuing regional tensions, September 21, 2026.
- World Food Programme — Projected Increase in Acute Food Insecurity Due to the Middle East Conflict, April 2, 2026.
- United Nations — Statement by Inter-Agency Standing Committee Principals concerning violations of the rules of war and attacks on civilian infrastructure, April 11, 2026.
- Reuters — UN mission findings concerning U.S. strikes in Iran and Iranian government abuses, September 17, 2026.
Research cutoff: September 21, 2026. This article combines reports, official releases, financial disclosures, commodity data, historical analysis and the previous Pattern Nexus research record. Observation dates vary by dataset. Estimates and forecasts are identified as such. Named officials' disclosed financial holdings are distinguished from allegations of motive or unlawful trading.
Method: Pattern Nexus follows the physical operating system, the ownership of its cash flows, the financing structure and the distribution of economic consequences. A proposed causal relationship is not treated as proven coordination. Scenarios are conditional and must be revised as contrary or additional evidence appears.
Financial risk notice: This article is independent economic and geopolitical research. It is not personalized investment advice or an instruction to buy, sell or hold securities, commodities or other financial instruments.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Founder of Pattern Nexus. I research markets, macro, geopolitics, AI, history, ancient systems, and the patterns most people overlook. I’m also building Market Radar, a trading scanner designed to read pressure, risk, confirmation, and setup quality before chasing a move. Pattern Nexus is where I connect the dots between data, history, technology, and the bigger system playing out around us.
Comments (0)